
▲ S&P 500 +—%|▲ Stock Advisor +—%Join The Motley Fool
S&P 500
7,520.93
-0.4%
-29.01
DJI
52,231.89
-0.3%
-157.86
NASDAQ
25,065.87
-0.7%
-187.26
Bitcoin
$73,415.00
-1.8%
-$1,337.81
SPCX
$143.09
+0.7%
+$1.02
AAPL
$348.51
-0.6%
-$2.18
AMZN
$270.87
+1.5%
+$3.94
GOOG
$284.92
-0.4%
-$1.09
META
$641.39
+0.0%
+$0.02
MSFT
$533.16
-2.2%
-$12.02
NVDA
$168.89
-5.5%
-$9.78
TSLA
$379.78
+0.5%
+$1.73
Free ArticleExplore Premium Services
By Daniel Miller – Nov 10, 2026 at 7:30PM EST
Key Points
-
Rivian’s deliveries jumped from the second to third quarters, but its automotive gross profit didn’t .
-
Currently, Rivian is absorbing large upfront launch costs without the benefit of second and third shifts improving production efficiency yet.
-
Rivian’s automotive gross profit has much potential upside over the next 18 months as the company adds shifts and realizes more production efficiency.
Credit revenue
First, regulatory-credit revenue fell from $106 million in the second quarter to $81 million in the third quarter, a decline of roughly 24%. Credits still provided a substantial benefit, but a smaller one, and one that management previously expected “substantially” less support from during the second half of 2026.
Subtracting that revenue from reported automotive gross profit gives an illustrative loss of $142 million in Q2 versus $161 million in Q3. That’s a $19 million deterioration, smaller than the reported $44 million increase in automotive gross losses. These calculations leave other benefits and expenses intact; they just help give a slightly clearer picture of its automotive gross profit in a scenario where credit revenue becomes a nonfactor.
RIVN – Rivian Automotive
$13.70-$0.31 (-2.21%)
NASDAQ · As of 4:00 PM ET 11/10/26
Premium Feature
 Moneyball Superscore66/100
Key data points
Market capMarket cap calculated using publicly traded s outstanding only. Does not include unlisted, private, or dual-class non-traded s. Implied market cap may vary.$20.45B
Day’s range$13.46 – $14.28
52wk range$11.38 – $22.69
Volume26.7M
Avg volume25.3M
Gross margin4.03%
Bigger launch bill
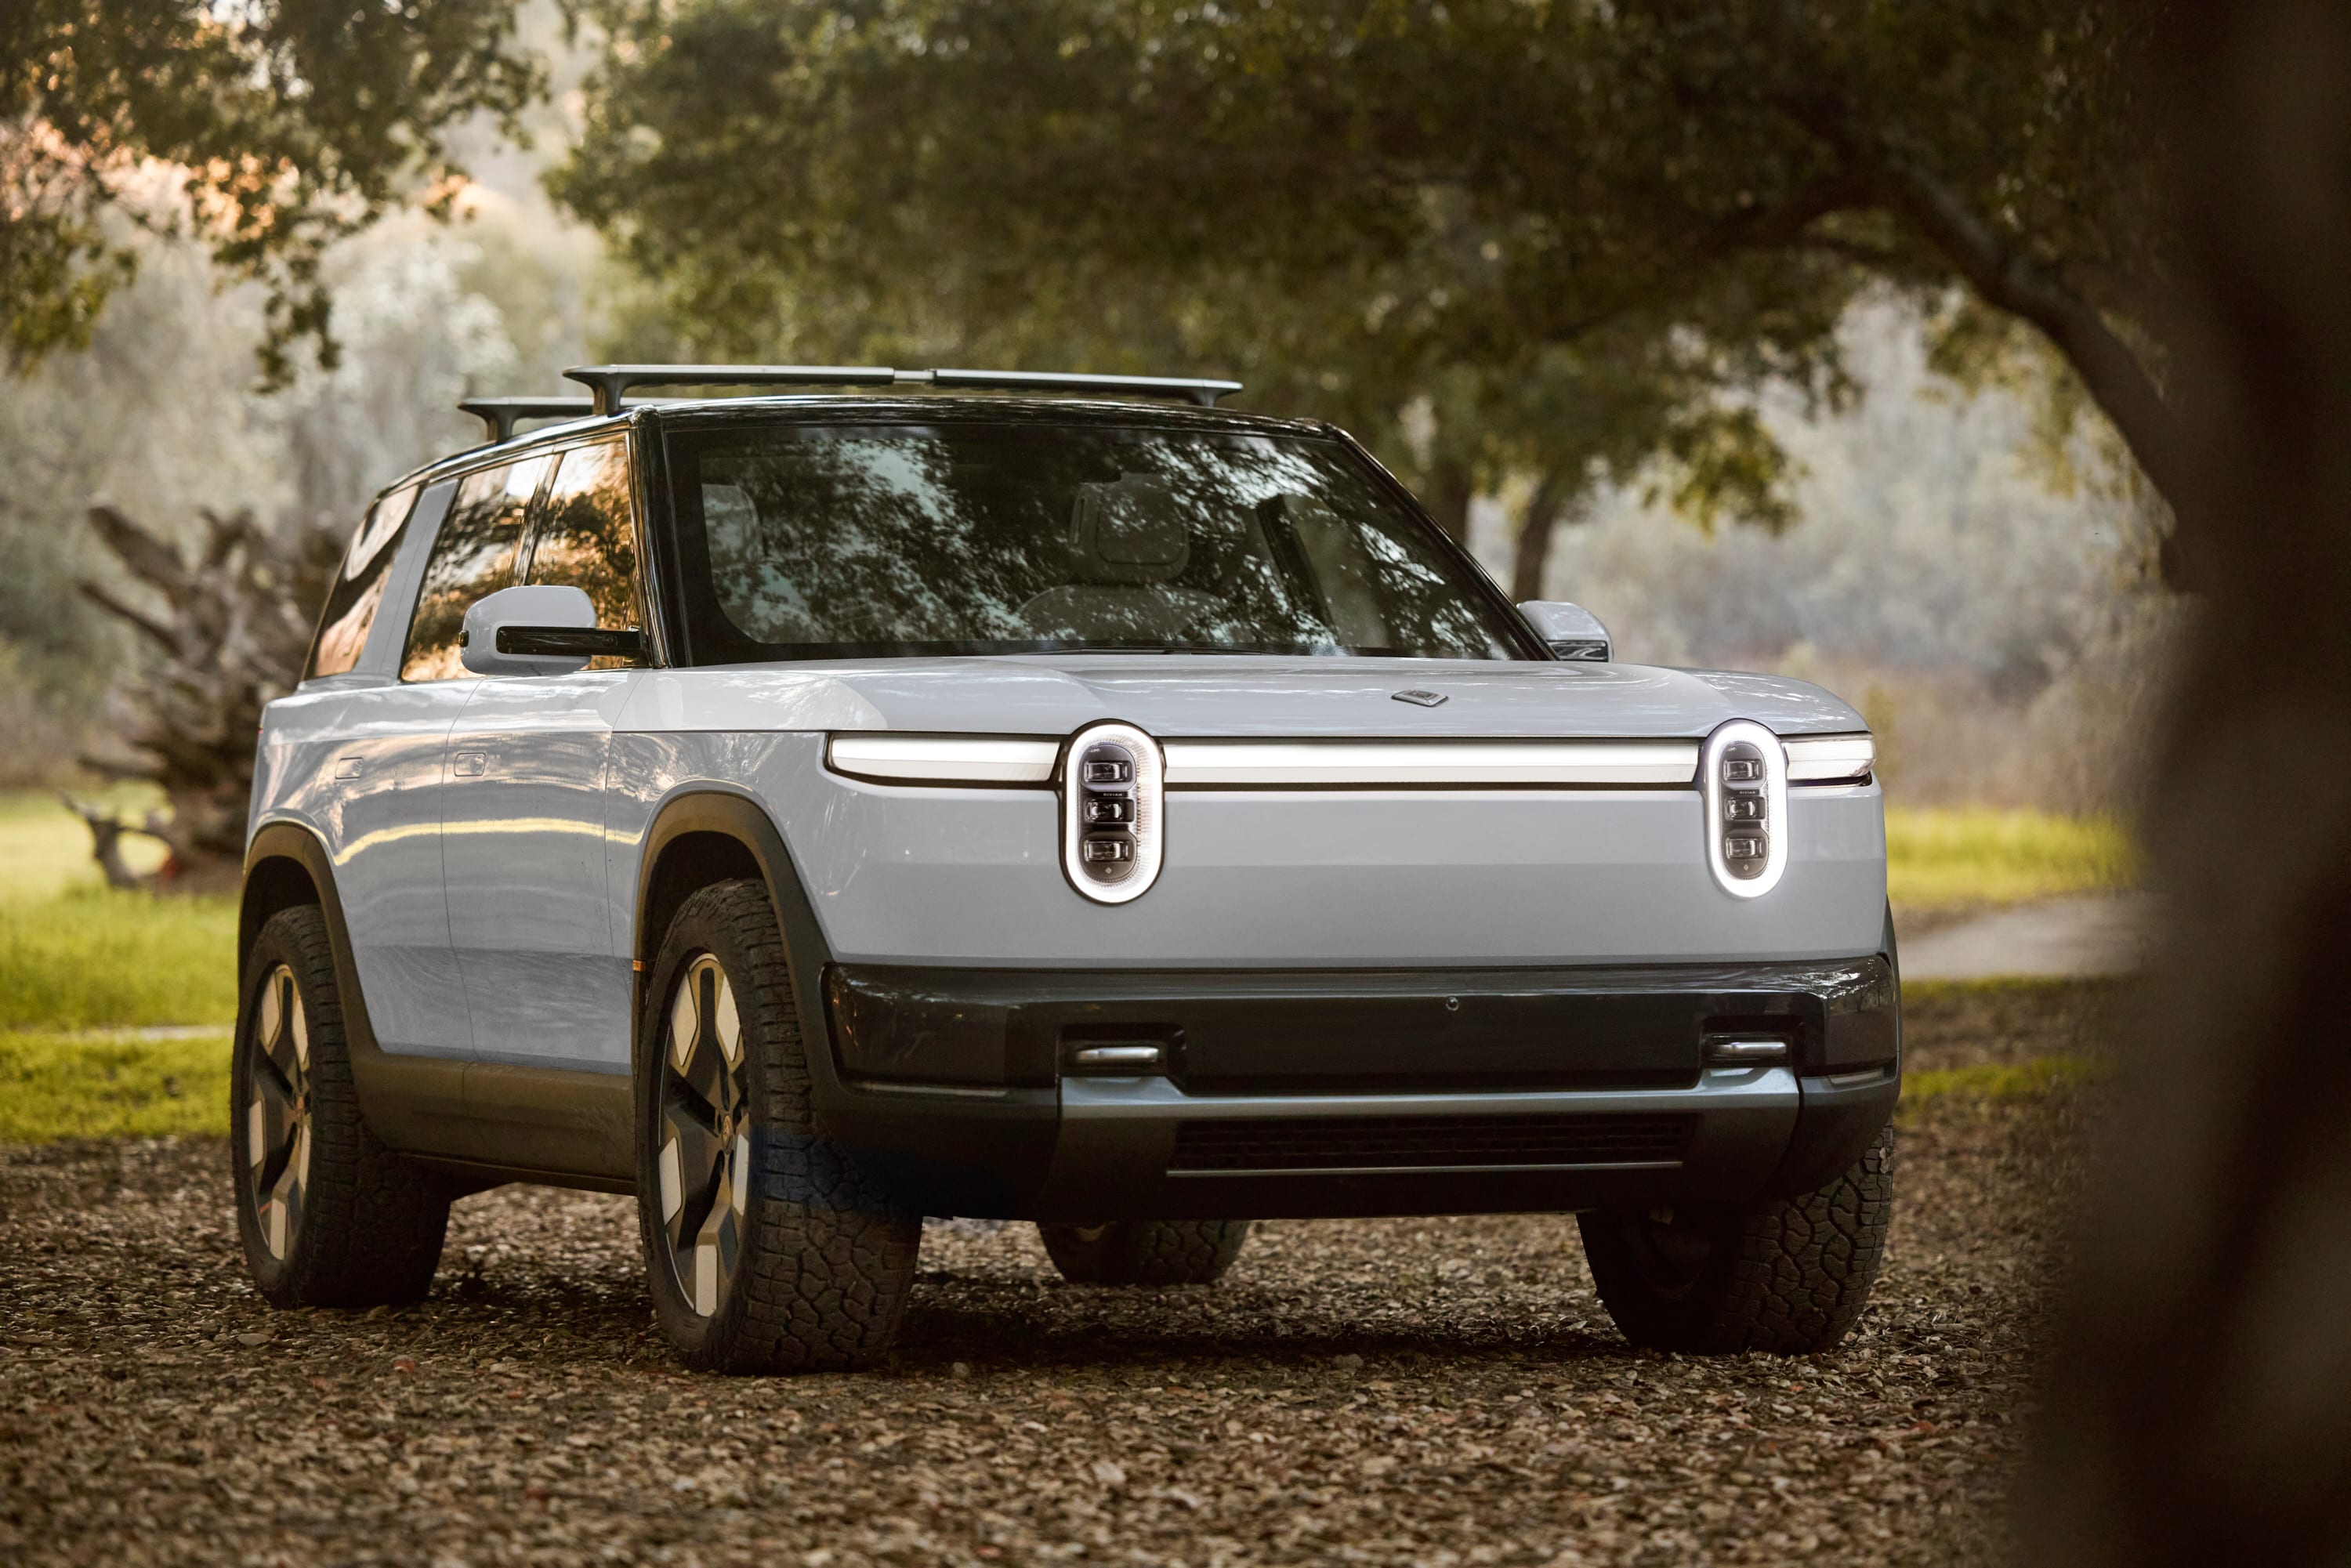
Second, Rivian recognized approximately $120 million in incremental R2 ramp costs, compared with roughly $100 million in Q2. Both figures measure costs relative to more normalized production levels. The entire $120 million wasn’t a new expense suddenly appearing this quarter.
Rivian explains that ramping up R2 can lead to higher costs while factory capacity remains underused. More production can improve efficiency without immediately overcoming those launch expenses. If you’re asking yourself how that works, good question. Part of that $120 million includes expenses such as expedited freight, while factory overhead is still spread across fewer vehicles than the planned two-shift operation could produce. Getting production running smoothly takes time — and the savings/efficiencies don’t arrive immediately.
There’s another complication: Tariff-refund receivables benefited automotive results in both quarters, but we don’t have specific information to know which quarter it benefited more. In other words, Rivian’s sales are accelerating, but launch costs and fluctuating benefits make its automotive gross profit progress harder to gauge.
What investors should watch
Rivian has delivery momentum. Now investors need to see its expanding production shifts and easing launch costs translate into sustained automotive gross profit, especially if regulatory credits and tariff-related benefits provide less support.
Software is doing its part, but its contribution can obscure what’s happening in the factory. Watching the two businesses separately will help investors judge whether R2 is delivering the financial progress they’re counting on. Keep in mind that in the near term, there’s ly more improvement upside in Rivian’s automotive segment, and realizing those gains will be a big step on its drive to reach breakeven and, eventually, bottom-line profits.
Don’t let one complicated quarter spoil the delivery celebration. Just remember that selling more vehicles is the beginning of the payoff, not the finish line. Rivian still needs to show it can consistently make money building them over the next year.
Where to invest $1,000 right now
When our analyst team has a stock tip, it can pay to listen. After all, Stock Advisor’s total average return is 852%* — a market-crushing outperformance compared to 208% for the S&P 500.
They just revealed what they believe are the 10 best stocks for investors to buy right now, available when you join Stock Advisor.
*Stock Advisor returns as of November 10, 2026.
Read Next
Prediction: Here’s What a $1,000 Investment in Rivian Will Be Worth by 2030 if the R2 Ramp Holds
Did I Call the Bottom With Rivian Stock?
•By Daniel Miller
Rivian’s R2 Is Winning More Than Trophies and Fans
•By Leo Sun
•By Joe Tenebruso
•By Robert Izquierdo
Stock Market Today, Nov. 2: Rivian Rallies on UBS Upgrade and Solid R2 Demand Outlook
About the Author

Daniel Miller is a contributing Motley Fool stock market analyst covering industrials and consumer goods, with a focus on automotive companies. He previously worked as a product manager in the automotive aftermarket industry. Miller holds a bachelor’s degree in business management from Emporia State University.
Stocks Mentioned

Rivian Automotive
NASDAQ: RIVN
$13.70
(-2.21%)-$0.31

Motley Fool Stock Advisor’s Latest Pick
—% Avg Return
*Average returns of all recommendations since inception. Cost basis and return based on previous market day close.
Premium Investing Services
Invest better with The Motley Fool. Get stock recommendations, portfolio guidance, and more from The Motley Fool’s premium services.
Sumber Artikel:
Fool.com

