
▲ S&P 500 +—%|▲ Stock Advisor +—%Join The Motley Fool
What Nvidia has working in its favor
Nvidia is the poster child of the current AI boom, with its hardware (especially its GPUs) powering the most advanced AI models around. Nvidia’s GPUs were initially used for video games, but they’re also great at the processing required to train and run AI models.
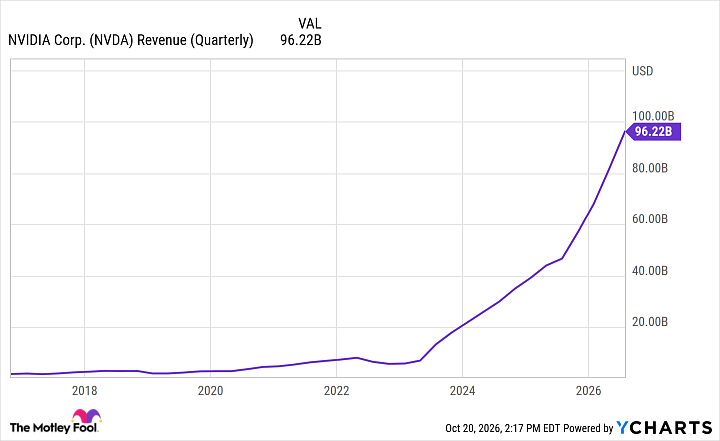
In its fiscal second quarter (ended July 26), Nvidia reported $96.2 billion in revenue (up 106% year over year), with $89 billion from its data center segment (up 117% year over year).
NVDA Revenue (Quarterly) data by YCharts
Nvidia is more than just its advanced chips. It’s done a great job of building a hardware-software ecosystem that essentially traps customers in because it’s the de facto coding language used in AI development (called CUDA), and switching to a different chipmaker would be too costly and time-consuming for companies.
This stronghold in enterprise AI is how Nvidia has become the world’s most valuable public company, with a market cap of over $5.2 trillion (as of market open on Oct. 21).
NVDA – Nvidia
$210.96-$1.25 (-0.59%)
NASDAQ · As of 4:00 PM ET 10/23/26
Premium Feature
 Moneyball Superscore97/100
Key data points
Market capMarket cap calculated using publicly traded s outstanding only. Does not include unlisted, private, or dual-class non-traded s. Implied market cap may vary.$5.11T
Day’s range$210.18 – $213.85
52wk range$164.27 – $243.37
Volume80.2M
Avg volume117.5M
Gross margin74.67%
Dividend yield0.25%
What TSMC has working in its favor
TSMC is the world’s premier semiconductor (chip) foundry and is also extremely important to the AI ecosystem, but for a different reason. While companies Nvidia design the chips they sell, TSMC manufactures them and brings them to life.
None of TSMC’s competitors can match its scale or capabilities, which is why it has long been the go-to for some of the world’s top tech giants — including Nvidia. When it comes to manufacturing advanced AI chips, TSMC has a monopoly, and that’s putting it lightly.
Being the go-to option has given TSMC significant pricing power, which it has used to its advantage. Its revenue growth is solid, but its margins are where its pricing power really shows up. From last third quarter to this recent third quarter, its gross margins rose from 59.5% to 66.4%, operating margin from 50.6% to 58.7%, and net profit margin from 45.7% to 51.1%.
This should continue. During TSMC’s latest earnings call, CEO C.C. Wei highlighted the demand, saying:
The AI market continues to be very strong. Recent developments are very positive to AI’s long-term demand outlook. We observe increasing AI demand, fueled by the rising adoption of agentic AI as we transition from chatbot to AI assistance.
TSM – Taiwan Semiconductor Manufacturing
$418.51+$6.16 (+1.49%)
NYSE · As of 4:00 PM ET 10/23/26
Premium Feature
Moneyball Superscore98/100
Key data points
Market capMarket cap calculated using publicly traded s outstanding only. Does not include unlisted, private, or dual-class non-traded s. Implied market cap may vary.$2.14T
Day’s range$411.11 – $421.31
52wk range$266.82 – $487.47
Volume9.5M
Avg volume11M
Gross margin65.07%
Dividend yield0.91%
Which is the better investment for the next five years?
From a business standpoint, one reason I give TSMC the edge is because of how much Nvidia depends on it. Nvidia is a powerhouse, no doubt, but without TSMC’s manufacturing ability, Nvidia’s business becomes limited. It’s at the mercy of TSMC’s capacity and production timelines.
TSMC is a great partner, but that dependency can also be a single point of failure. I don’t see it happening, but the risk is there nonetheless. Nvidia could go with a rival Samsung, but that could mean sacrificing production and having to redesign systems.
The same concentration risk applies to many other tech companies. Regardless of who dominates the AI race between the AI hyperscalers (Amazon, Microsoft, Alphabet, and Meta Platforms), they’ll all rely on TSMC for manufacturing. That puts TSMC in a very lucrative position for at least the next five years, but even after the AI frenzy, it’ll remain a key piece in the supply chain for tons of other electronics.
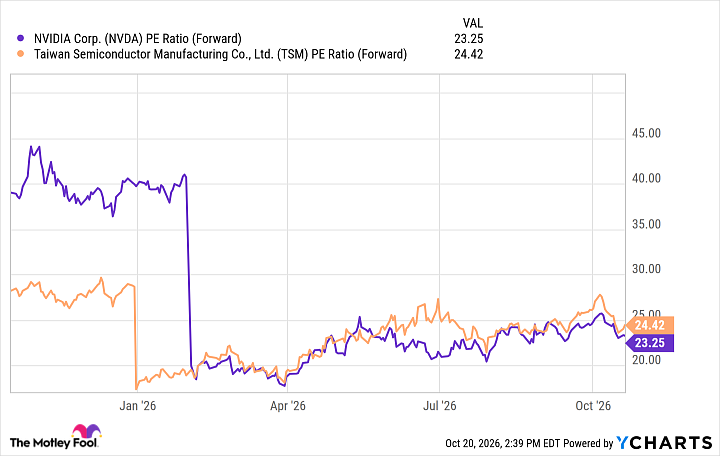
From a stock standpoint, Nvidia and TSMC trade similarly, at 23.3 and 24.2 times their projected earnings next year, respectively. However, the difference in market caps ($5.2 trillion versus $2.2 trillion) leads me to believe that TSMC has more upside. It could double in value and still not be as valuable as Nvidia is now.
NVDA PE Ratio (Forward) data by YCharts
We can’t predict how any stock will perform, and you ly can’t go wrong with investing in either stock. However, over the next five years, I TSMC’s upside.
Read Next
Prediction: Nvidia Will Outperform Broadcom Over the Next 5 Years
•By John Ballard
3 Magnificent AI Chip Stocks That Could Help Set You Up for Life
September 2026 Mailbag: 16 Years Old to 25 Years Foolish
•By Patrick Sanders
The AI Bottleneck Takes Many Forms. These 7 Stocks Will Benefit.
•By Frank Bass
Can You Invest in Project Omega in 2026? Details & Alternatives
•By Keithen Drury
Is Nvidia a Top Quantum Computing Stock?
About the Author

Stefon Walters is a contributing Motley Fool stock market analyst covering publicly traded companies across technology, consumer goods, and financials, as well as retirement planning. Stefon is a published author and has more than a decade of experience teaching financial literacy. He holds a bachelor’s degree in economics from the University of North Carolina at Chapel Hill.
Stocks Mentioned

Nvidia
NASDAQ: NVDA
$210.96
(-0.59%)-$1.25

Motley Fool Stock Advisor’s Latest Pick
—% Avg Return

Taiwan Semiconductor Manufacturing
NYSE: TSM
$418.51
(+1.49%)+$6.16
*Average returns of all recommendations since inception. Cost basis and return based on previous market day close.
Premium Investing Services
Invest better with The Motley Fool. Get stock recommendations, portfolio guidance, and more from The Motley Fool’s premium services.
Sumber Artikel:
Fool.com

