
▲ S&P 500 +—%|▲ Stock Advisor +—%Join The Motley Fool
S&P 500
7,520.93
-0.4%
-29.01
DJI
52,231.89
-0.3%
-157.86
NASDAQ
25,065.87
-0.7%
-187.26
Bitcoin
$73,415.00
-1.8%
-$1,337.81
SPCX
$143.09
+0.7%
+$1.02
AAPL
$348.51
-0.6%
-$2.18
AMZN
$270.87
+1.5%
+$3.94
GOOG
$284.92
-0.4%
-$1.09
META
$641.39
+0.0%
+$0.02
MSFT
$533.16
-2.2%
-$12.02
NVDA
$168.89
-5.5%
-$9.78
TSLA
$379.78
+0.5%
+$1.73
Free ArticleExplore Premium Services
By Daniel Miller – Nov 10, 2026 at 7:30PM EST
Key Points
-
BYD’s Q3 revenue jumped 13.6%, and net profits rose about 28% compared to the prior year.
-
The rise in revenue ended four consecutive quarters of declines.
-
Exporting vehicles is giving BYD a way to offset domestic struggles — but will that continue?
OTC · As of 3:52 PM ET 11/10/26
Key data points
Market capMarket cap calculated using publicly traded s outstanding only. Does not include unlisted, private, or dual-class non-traded s. Implied market cap may vary.$83.78B
Day’s range$8.83 – $9.42
52wk range$8.50 – $14.95
Volume81.6K
Avg volume148.9K
Gross margin24.60%
Dividend yield0.58%
1. Can China start helping again?
BYD’s global vehicle sales increased 18.8% in Q3, to more than 1.32 million. Overseas shipments more than doubled, helping offset weaker sales in China, according to Reuters.
That’s been the strategy of BYD, and just about every other automaker competing in China, because China’s domestic auto market sales hit a speed bump and remain in a brutal price war — a nasty combination. An expanding international business gives BYD another place to find customers when its home market gets tougher, especially if overseas sales prove more profitable until China’s market balances and the price war lightens. That said, investors would have a stronger BYD rebound on their hands if China stopped needing to be offset.
Competition remains fierce. Rival Geely‘s faster-charging technology is expanding its network, and competitively priced vehicles from Stellantis-backed Leapmotor are giving consumers more options. For all of Tesla‘s (TSLA +0.46%) woes, its product lineup remains surprisingly resilient considering the lack of major vehicle refreshes or launches. For investors, the next encouraging development would be a recovery in domestic sales alongside continued improvement in companywide profitability. That would give BYD’s rebound a broader foundation and offer investors more reason to celebrate.
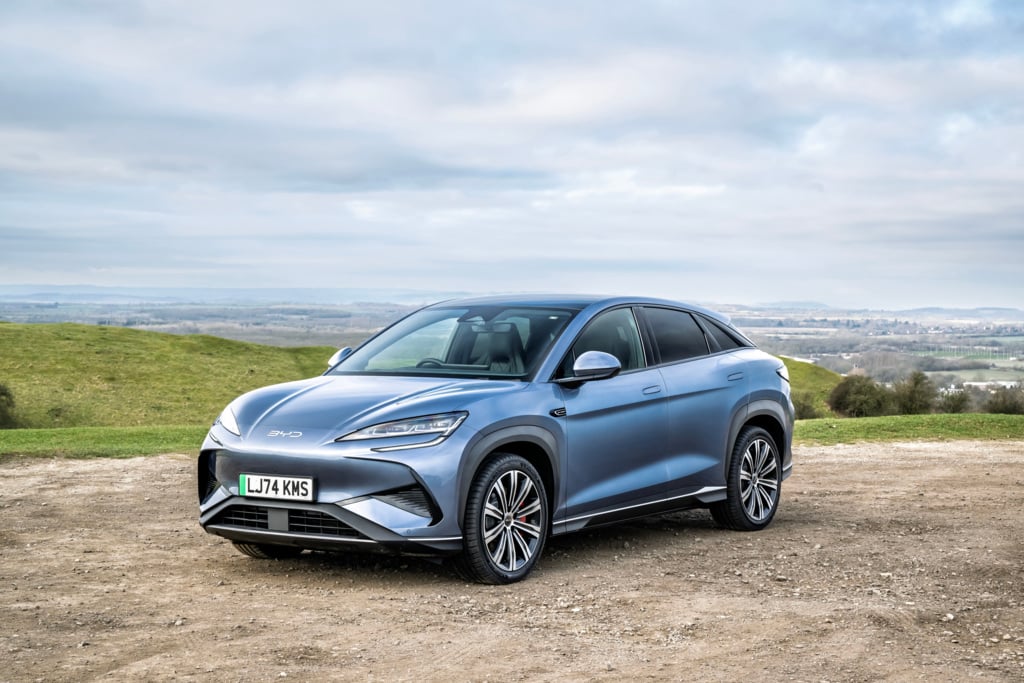
Image source: BYD Co.
2. Will overseas growth keep paying off?
Export growth gives BYD an opportunity, but a passport isn’t a guarantee of profits, because there are familiar faces joining the overseas auto battle. Competition from other Chinese automakers is also intensifying overseas. BYD’s international expansion therefore shouldn’t be treated as an escape hatch from competitive pressure.
In fact, BYD’s Chinese rival Geely has the same playbook and offers a perfect example. Geely’s Q3 net profit also increased roughly 28%, with overseas growth helping counter slowing demand in China. That’s encouraging for the industry, but it also reminds investors that BYD’s competitors have passports, too. On the other hand, what nobody wants is for Chinese automakers to export their domestic price war to the rest of the world.
Investors should watch whether growing overseas sales continue translating into stronger companywide earnings. It would also be useful to see more detail on regional profitability before assuming every vehicle sold abroad delivers superior returns. Investors will also want to watch which Chinese or other new foreign competitors can better avoid or offset some tariffs or set up local operations to gain a competitive edge.
There’s an important distinction here: Expanding into more markets can make a business more diversified without automatically making each sale more profitable. BYD needs both the customers and the economics to make its expansion more valuable.
What it all means
The quarter offers encouragement: Revenue returned to growth and profit increased. But the investment case needs more than a better-looking earnings headline. A healthier domestic business would give the recovery a second engine. Overseas expansion that supports lasting profit growth would make it more convincing still, especially if it can hold advantages overseas while avoiding a relocated Chinese price war.
On that note, investors don’t need BYD to win every price war. They need evidence that the company can keep growing and leveraging its numerous competitive advantages into more durable profits.
Where to invest $1,000 right now
When our analyst team has a stock tip, it can pay to listen. After all, Stock Advisor’s total average return is 852%* — a market-crushing outperformance compared to 208% for the S&P 500.
They just revealed what they believe are the 10 best stocks for investors to buy right now, available when you join Stock Advisor.
*Stock Advisor returns as of November 10, 2026.
Read Next
•By Matt DiLallo
How to Buy BYD Stock (BYDDF) in 2026
•By Daniel Miller
Rivian’s Deliveries Jumped 58%. Why Didn’t Gross Profit ?
•By Keith Noonan

•By Lee Samaha
•By Joe Tenebruso
•By Stefon Walters
S&P 500 Sell-Off: 1 Investing Step to Take Right Now, and 1 Risky Move to Avoid
About the Author

Daniel Miller is a contributing Motley Fool stock market analyst covering industrials and consumer goods, with a focus on automotive companies. He previously worked as a product manager in the automotive aftermarket industry. Miller holds a bachelor’s degree in business management from Emporia State University.
Stocks Mentioned

BYD
OTC: BYDDF
$9.07
(-1.41%)-$0.13

Motley Fool Stock Advisor’s Latest Pick
—% Avg Return

Tesla
NASDAQ: TSLA
$379.78
(+0.46%)+$1.73

Geely Automobile
OTC: GELYF
$1.83
(0.00%)+$0.00

Stellantis
NYSE: STLA
$4.26
(-3.62%)-$0.16
*Average returns of all recommendations since inception. Cost basis and return based on previous market day close.
Premium Investing Services
Invest better with The Motley Fool. Get stock recommendations, portfolio guidance, and more from The Motley Fool’s premium services.
Sumber Artikel:
Fool.com

