
▲ S&P 500 +—%|▲ Stock Advisor +—%Join The Motley Fool
Burry’s bet now stretches into 2027
Burry has been betting against Palantir since the fall of 2025. In April, he wrote that he thinks the company’s fundamental value is well below $50 a .
Later, in a Sept. 28 post, he said he was moving his timeline up. He traded his outright short positions in Palantir and seven other holdings for put options expiring between June and December 2027, arguing that the AI build-out is increasingly funded by debt and might fall apart if spending slows.
Burry has also questioned Palantir’s accounting, in a February post arguing that its accounts receivable climbed faster than its revenue in nine of 12 quarters.
But put options expire. For Burry’s puts to pay off, Palantir’s growth probably has to slow sharply in the coming year or so, and the Nov. 2 report is the next chance to tell if that’s starting.
A faster quarter than guided?
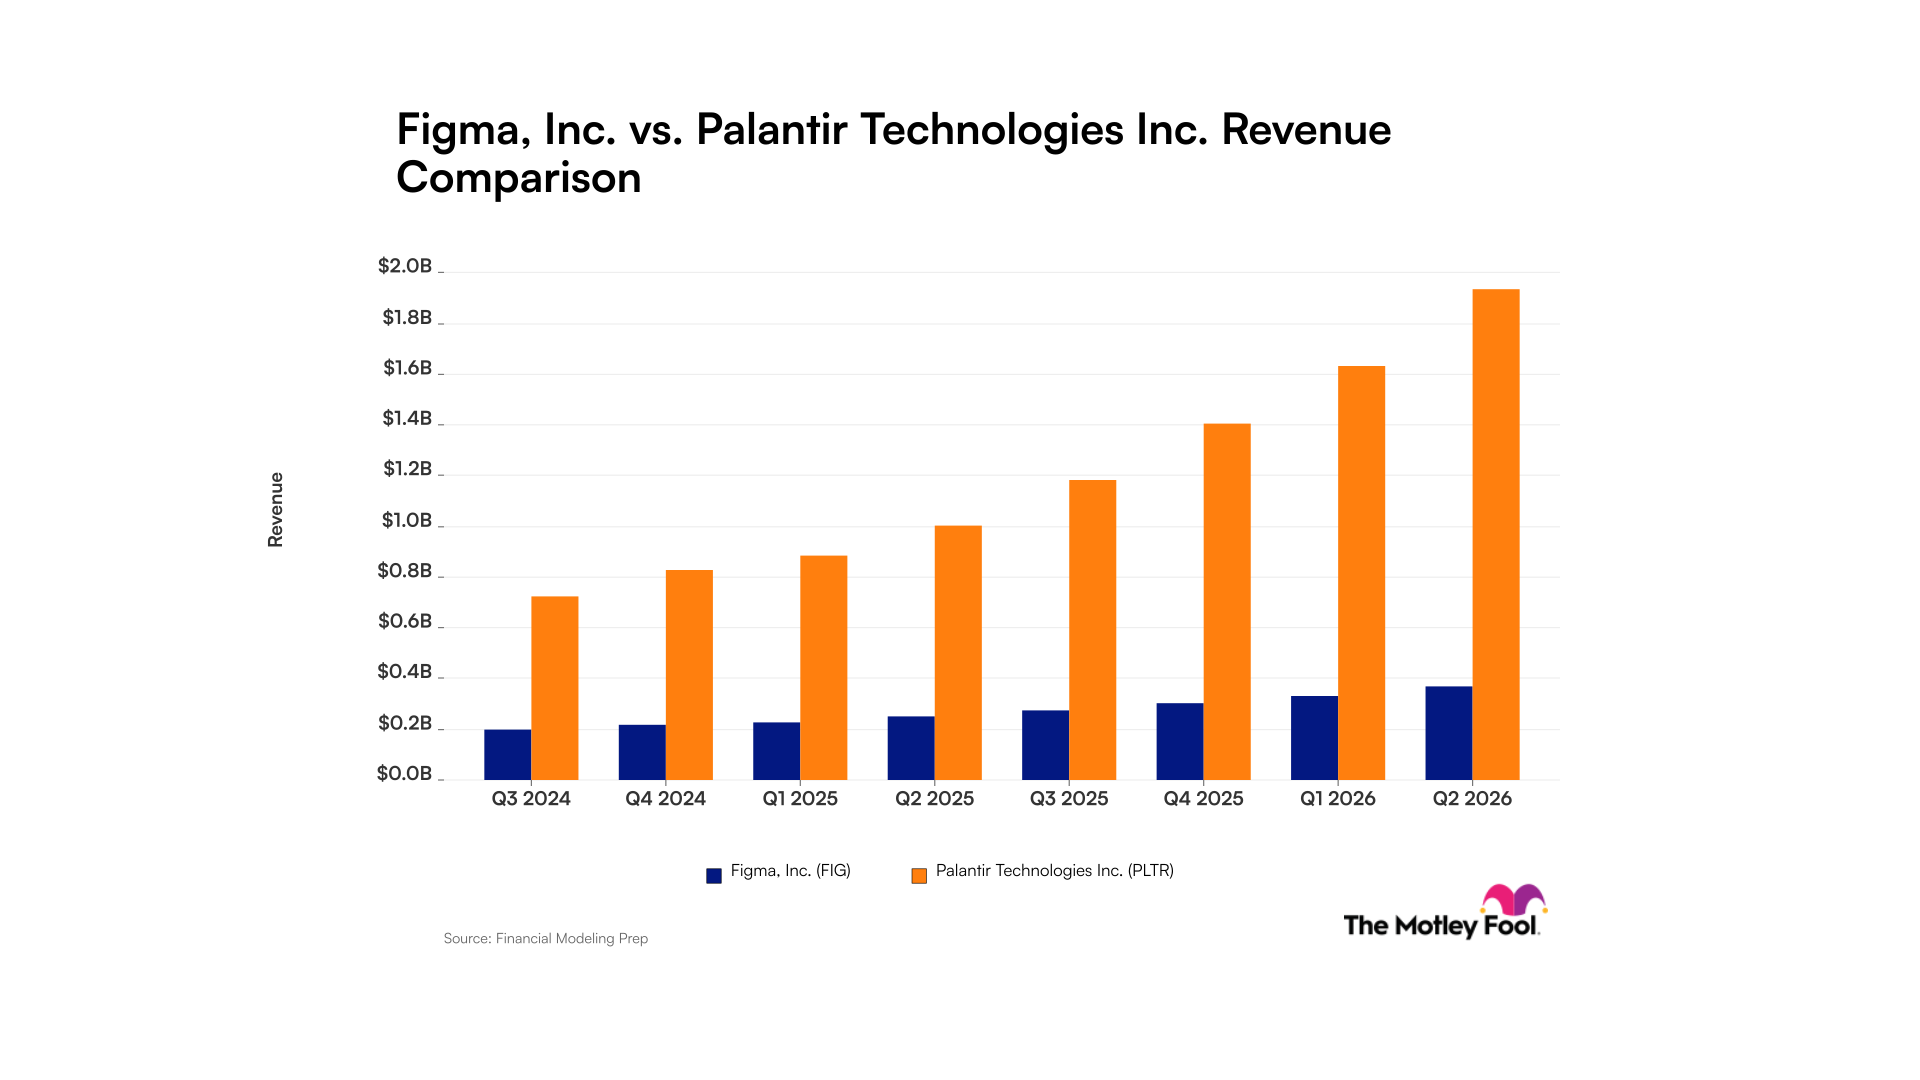
Palantir’s guidance calls for third-quarter revenue of $2.160 billion to $2.164 billion. Compared to $1.18 billion in the year-ago quarter, that’s around 83% growth year over year, slower than 93% growth in the second quarter.
Palantir, however, tends to set its forecasts low. Its second-quarter revenue of $1.94 billion beat the top end of its own forecast by about 7%. In the first quarter of 2026, revenue of $1.63 billion beat the top end by about 6%. And in the fourth quarter of 2025, revenue of $1.41 billion cleared it by about 6% too.
If the third quarter clears its range by a similar margin, revenue could land around $2.3 billion. That would mean growth of about 95%, a little faster than in the second quarter. A result close to $2.16 billion, though, might suggest that growth slowed from the second quarter — the sort of slowdown Burry’s bet needs.
U.S. commercial has to keep climbing
The second number is U.S. commercial revenue (what Palantir sells to American companies instead of to government agencies). It is growing far faster than Palantir’s overall revenue, and the full-year outlook leans on it most.
Showing how quickly that business has scaled, Palantir’s U.S. commercial revenue climbed 149% year over year to $764 million in the second quarter. That was faster than its 133% growth in the first quarter. Quarter over quarter, the business grew 28% in the second quarter, after 18% in the first.
Management expects U.S. commercial revenue of at least $3.424 billion in 2026. The first half brought in about $1.36 billion, so the second half needs about $2.07 billion — over twice the $904 million in the second half of 2025. This probably means quarter-over-quarter growth of about 22% in each of the final two quarters, or third-quarter U.S. commercial revenue of about $930 million.
PLTR – Palantir Technologies
$184.11-$12.31 (-6.27%)
NASDAQ · As of 4:00 PM ET 10/30/26
Premium Feature
 Moneyball Superscore89/100
Key data points
Market capMarket cap calculated using publicly traded s outstanding only. Does not include unlisted, private, or dual-class non-traded s. Implied market cap may vary.$442.43B
Day’s range$180.81 – $193.92
52wk range$106.37 – $212.94
Volume27.1M
Avg volume31.1M
Gross margin84.80%
A result well above that might suggest companies are still adopting Palantir’s software faster than its own forecast assumes. A result below it would put more weight on the fourth quarter and raise the chances that the full-year target slips.
Of course, even two strong numbers wouldn’t make the stock cheap. At about $195, the stock costs about 166 times the earnings Palantir reported in its past four quarters. Even against the adjusted earnings analysts expect for 2027, s cost about 84 times earnings.
Still, a strong report might make Burry’s under-$50 view hard to accept. After all, at $50, s would cost about 43 times reported earnings, a modest price for a growth stock whose revenue rose 93% in its latest quarter.
In the end, if the report shows revenue around $2.3 billion and U.S. commercial sales of about $930 million or more, I think Burry’s case gets harder to defend. But that wouldn’t change my view of the stock’s valuation. I’d want s closer to $140, or about 120 times reported earnings, before I’d consider buying.
Read Next
•By Adam Spatacco
Should You Buy Palantir Stock Before Nov. 2?
Should You Buy Palantir Stock Before the Huge Investor Update?
•By Robert Izquierdo
Palantir Technologies vs. Figma: Comparing Revenue Growth Trends
•By Scott Levine
How to Buy Pony AI Stock (PONY) in 2026
•By Leo Sun
Could $1,000 Invested in Palantir Turn Into $100,000?
•By Keithen Drury
What a $1,000 Investment in Palantir Could Be Worth by the End of 2027 (The Answer May Surprise You)
About the Author

Daniel Sparks is a contributing Motley Fool stock market analyst covering technology, industrials, financials, and consumer goods. Daniel is the owner and chief investment officer of Sparks Capital Management. He holds a master’s degree in business administration from Colorado State University. The Globe and Mail profiled him and his investing philosophy in an article titled, “This stock picker is outperforming nearly everybody else. Here’s how he is doing it.”
Stocks Mentioned

Palantir Technologies
NASDAQ: PLTR
$184.11
(-6.27%)-$12.31

Motley Fool Stock Advisor’s Latest Pick
—% Avg Return
*Average returns of all recommendations since inception. Cost basis and return based on previous market day close.
Premium Investing Services
Invest better with The Motley Fool. Get stock recommendations, portfolio guidance, and more from The Motley Fool’s premium services.
Sumber Artikel:
Fool.com

