
▲ S&P 500 +—%|▲ Stock Advisor +—%Join The Motley Fool
Highly encouraging efficacy
That morning, Bristol Myers Squibb announced that the drug, izalontamab brengitecan (iza-bren), delivered positive results in a Phase 3 head-to-head trial versus platinum-based chemotherapy (PBC). The patients participating in the study had a form of non-small cell lung cancer (NSCLC) and had previously been treated with a type of medication known as an EGFR tyrosine kinase inhibitor (TKI).
The trial readout indicated that the drug significantly prolonged progression-free survival (PFS). The median PFS for those taking iza-bren was 11.1 months, which compared favorably with 5.7 months for patients in the chemotherapy control arm.
Bristol Myers Squibb added that iza-bren demonstrated a manageable safety profile in the study, with treatment-related adverse events consistent with those observed in earlier testing.
The clinical trial was administered by Sichuan Biokin Pharmaceutical, a Chinese company that is the parent of the drug’s developer, SystImmune. In December 2023, Bristol Myers Squibb announced it had struck an exclusive licensing and collaboration agreement with SystImmune to advance iza-bren. Under its terms, the U.S.-based company holds the development and commercialization rights for all countries outside of mainland China and the U.S. SystImmune holds those rights exclusively in the former, while the two companies the development and commercialization rights on our shores.
In the deal, Bristol Myers Squibb made an $800 million upfront payment and is on the hook for as much as $500 million in contingent near-term payments. It is also obligated to pay up to $7.1 billion if certain developmental, regulatory, and commercial milestones are reached.
In its latest press release on iza-bren, the company touted that this is the fifth solid tumor type in which the drug has demonstrated efficacy. Bristol Myers Squibb’s chief medical officer Cristian Massacesi was quoted as saying that this performance “is highly encouraging and speaks to the potential of iza-bren to address significant unmet needs in oncology.”
BMY – Bristol Myers Squibb
$61.61+$0.13 (+0.21%)
NYSE · As of 4:00 PM ET 10/26/26
Premium Feature
 Moneyball Superscore68/100
Key data points
Market capMarket cap calculated using publicly traded s outstanding only. Does not include unlisted, private, or dual-class non-traded s. Implied market cap may vary.$125.85B
Day’s range$61.11 – $62.06
52wk range$42.52 – $68.64
Volume7.8M
Avg volume11.7M
Gross margin66.64%
Dividend yield4.09%
Muted reaction
That’s certainly true, so why didn’t Bristol Myers Squibb’s stock pop higher on the news? After all, the world is hungry for efficacious cancer drugs, and iza-bren appears to fit the bill.
I believe the main reason is that the study (along with the other four solid-tumor trials) was conducted in mainland China. And no matter how well a drug performs there, the U.S. Food and Drug Administration (FDA) generally rejects approval based solely on single-country, China-only data, without multi-region confirmatory data that meet Western standards of care. So it’s ly that approval inside our borders or with top healthcare regulators abroad, such as the European Medicines Agency, is still years away, at best.
As for the study itself, Bristol Myers Squibb said that data for overall survival (OS) — an important endpoint with cancer drugs — were immature. OS is rightfully considered a more meaningful indicator of a medication’s ultimate impact, especially since subsequent crossover therapies can dilute initial PFS gains.
Also, since it’s saddled with a legacy portfolio of drugs that have either fallen off the patent cliff or are rapidly approaching it, even a blockbuster product won’t suddenly make a night-and-day difference to the company. Another factor is that iza-bren isn’t the only dog in the fight; competitors such as Johnson & Johnson (JNJ +0.94%) are developing comparable drugs targeting solid tumors.
That’s why I think investors shouldn’t base their Bristol Myers Squibb investment decision on the latest iza-bren news alone. That said, it’s an exciting development program well worth keeping an eye on, particularly given the company’s concerted effort to move away from its fading legacy product line to bolster the growth portfolio. Iza-bren could be a strong product if it performs well in trials outside of China and eventually wins approval.
Read Next
•By James Brumley
3 Cheap Dividend Stocks I’d Buy Without Any Hesitation
Bristol Myers Squibb: Bargain Buy or Value Trap?
•By Keith Speights
3 High-Yield Stocks to Buy With $1,000 Right Now
Should You Buy Bristol Myers Squibb While It Trades Below 10 Times Forward Earnings?
•By Keith Speights
Better Dividend Stock to Buy and Hold: Pfizer or Bristol Myers Squibb?
•By Brendan Coffey
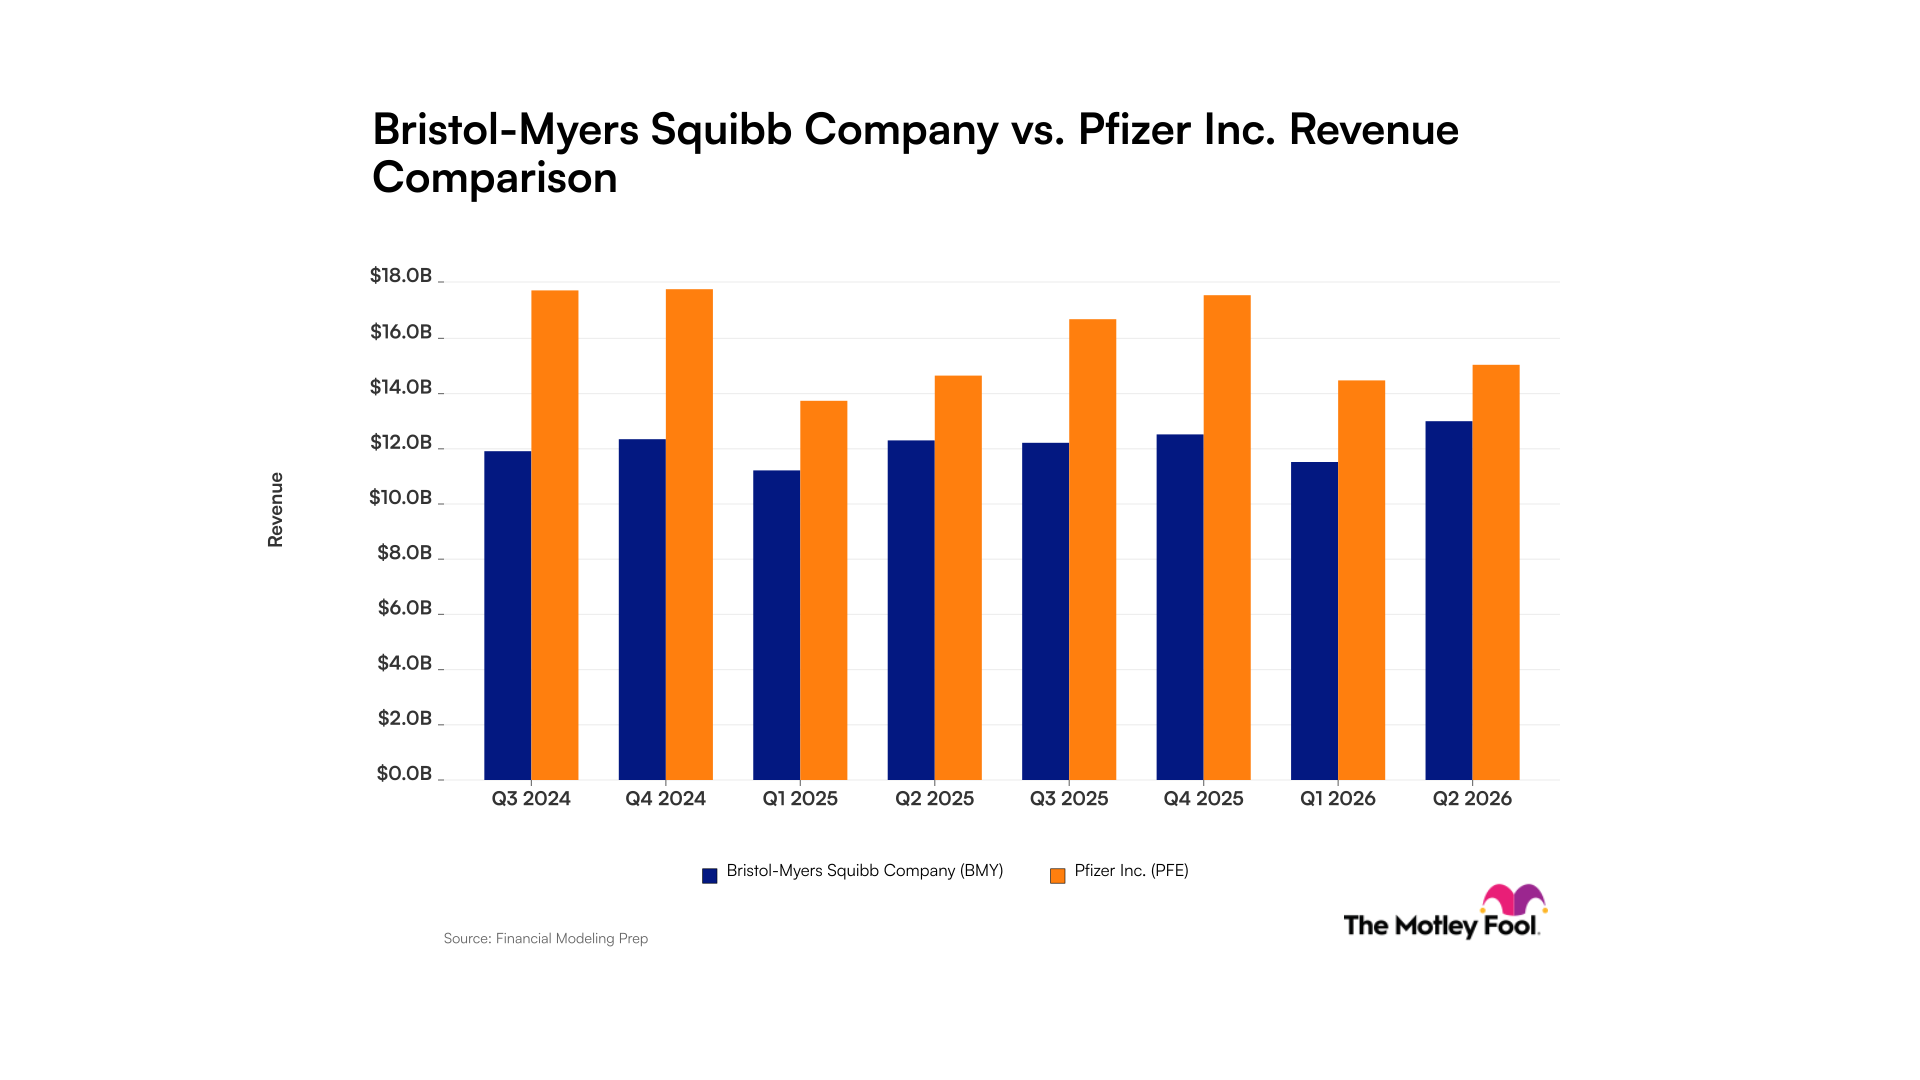
Bristol Myers Squibb vs. Pfizer: Consistency vs. Scale in Revenue
About the Author

Eric Volkman is a contributing Motley Fool finance and stock market analyst. Previously, Eric was an equities analyst at European investment bank Raiffeisen Capital and Investment. He’s also been a freelance finance writer since 1995. He studied at Susquehanna University.
Stocks Mentioned

Bristol Myers Squibb
NYSE: BMY
$61.61
(+0.21%)+$0.13

Motley Fool Stock Advisor’s Latest Pick
—% Avg Return
*Average returns of all recommendations since inception. Cost basis and return based on previous market day close.
Premium Investing Services
Invest better with The Motley Fool. Get stock recommendations, portfolio guidance, and more from The Motley Fool’s premium services.
Sumber Artikel:
Fool.com

