
▲ S&P 500 +—%|▲ Stock Advisor +—%Join The Motley Fool
Lumentum is benefiting from the next big bottleneck in AI infrastructure
AI chips, such as graphics cards and custom AI processors, are capable of processing huge data sets quickly. However, they need rapid access to all that data to ensure that training and inference workloads can be handled seamlessly. This is why optical networking components are in terrific demand, as the limitations of traditional copper cables don’t hold them back.
LITE – Lumentum
$913.95+$47.77 (+5.51%)
NASDAQ · As of 4:00 PM ET 10/28/26
Premium Feature
 Moneyball Superscore82/100
Key data points
Market capMarket cap calculated using publicly traded s outstanding only. Does not include unlisted, private, or dual-class non-traded s. Implied market cap may vary.$82.79B
Day’s range$872.40 – $921.00
52wk range$184.20 – $1,143.00
Volume5.9M
Avg volume4.9M
Gross margin39.74%
However, healthy demand for optical networking is creating a significant supply shortage, as production isn’t keeping pace. Consulting giant McKinsey estimates that the production of high-speed optical transceivers could fall significantly short of demand through 2029.
For instance, the supply of transceivers capable of transmitting data at 1.6 terabits per second (1.6 Tbps) could be 30% to 40% below demand through 2029. Meanwhile, the demand for 800-Gbps transceivers could be 40% to 60% higher than supply through 2027. The incredible demand for optical networking and the severe supply shortage are driving up prices, significantly boosting Lumentum’s margins.
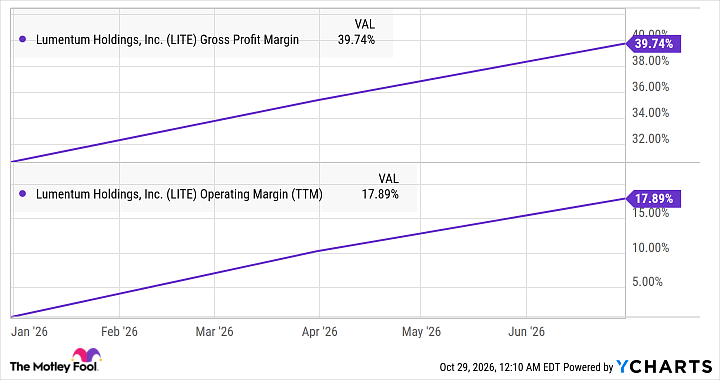
LITE Gross Profit Margin data by YCharts
Not surprisingly, analysts are expecting a 135% year-over-year increase in Lumentum’s revenue for the previous quarter to $1.25 billion, while adjusted earnings per (EPS) could jump by 284% to $4.22. Wall Street’s expectations are well within Lumentum’s fiscal Q1 guidance range. However, Lumentum could spring a positive surprise.
That’s because the optical networking market is poised for exponential growth. Goldman Sachs notes that optical networking revenue could jump from $15 billion in 2026 to $154 billion in 2028, a whopping 10x jump in just a couple of years. Lumentum is positioning itself to make the most of this huge opportunity by ramping up production of 1.6T transceivers in 2027.
Lumentum management indicated on the August earnings call that the shift toward 1.6T transceivers could boost its margins. CEO Michael Hurlston pointed out:
Meanwhile, profitability across our transceiver lines continues to improve, driven by gains in both yield and capacity utilization as well as the initial rollout of higher ASP 1.6T transceivers. Our visibility into future cloud transceiver demand is clearer than ever. In fact, we expect the 1.6T transceiver uptake to intensify starting in fiscal Q1 and sustain through calendar 2027.
So, Lumentum’s EPS growth could accelerate in the future. The company’s adjusted EPS in fiscal 2026 was $8.67. According to the ing chart, its bottom line could jump by 5.5x in just three years. However, we have seen that the optical networking market could clock a 10x jump between 2026 and 2028, according to Goldman Sachs.
As such, Lumentum is positioned to deliver a larger increase in earnings per . That’s why investors looking to buy a top growth stock should take a closer look at this name, especially considering that it has pulled back significantly this month.
Now is a great time to buy Lumentum stock
s of Lumentum have lost 19% of their value since Oct. 9, when the stock reached a 52-week high. As a result, investors can now buy Lumentum at 43 times forward earnings, which seems a good deal considering the incredible earnings growth it is poised to deliver.
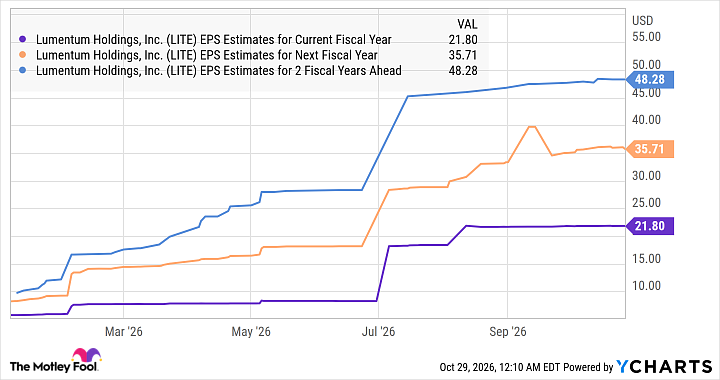
LITE EPS Estimates for Current Fiscal Year data by YCharts
Assuming Lumentum’s EPS jumps to $48.28 in fiscal 2029 and it trades at even 30 times earnings, a discount to the tech-laden Nasdaq Composite index’s average earnings multiple of 41, its stock price could soar to $1,448. That implies a potential gain of 58%. However, Lumentum’s outstanding earnings growth potential and its ability to outperform Wall Street’s expectations could help it command a premium valuation.
So, investors can expect bigger gains from this AI stock once it beats expectations in November, which is why buying Lumentum ahead of its earnings report could be a smart move given its attractive valuation.
Read Next
•By John Ballard
Lumentum vs. Sandisk: Which Tech Stock Is the Better Buy in November?
•By Scott Levine
Why Lumentum Holdings Stock Soared 8.2% Today
•By Patrick Sanders
The AI Bottleneck Takes Many Forms. These 7 Stocks Will Benefit.

•By John Ballard
Arm vs. Lumentum: Which Tech Stock Is a Better Buy in 2026?
•By Billy Duberstein

•By Sara Appino
Automatic Data Processing vs. Lumentum: Which Technology Stock Is a Better Buy in 2026?
About the Author

Harsh Chauhan is a contributing Motley Fool technology analyst covering semiconductors, consumer electronics, artificial intelligence, and software. Harsh previously worked as a journalist for CCN Markets covering crypto and macroeconomics, a contributor at Capital 10x covering metals, mining, and industrial stocks, and a research associate at Zacks Investment Research. He holds a bachelor’s degree in commerce from St. Xavier’s College in Kolkata, India.
Stocks Mentioned

Lumentum
NASDAQ: LITE
$913.95
(+5.51%)+$47.77

Motley Fool Stock Advisor’s Latest Pick
—% Avg Return
*Average returns of all recommendations since inception. Cost basis and return based on previous market day close.
Premium Investing Services
Invest better with The Motley Fool. Get stock recommendations, portfolio guidance, and more from The Motley Fool’s premium services.
Sumber Artikel:
Fool.com

