

The latest demand wave in this industry is unany other, and it could provide multiple years of elevated profitability that makes companies Micron (MU +0.81%) and Sandisk (SNDK -3.46%) viable investments. I think they’re well worth the investment right now, and I’ve got three reasons why they could defy history and be less cyclical over the next few years.
Image source: Getty Images.
1. Demand is still rising
AI demand from data centers has brought unprecedented demand to companies in many sectors. There are all sorts of companies benefiting from the hundreds of billions of dollars being spent on data centers right now, but memory chips are currently the biggest bottleneck. This industry wasn’t prepared for the huge demand rush, mainly because it had ample production capacity for normal demand volumes until the AI wave hit.
Expand

NASDAQ: MU
Micron Technology
Premium Feature
Moneyball Superscore
92/100
Today’s Change
(0.81%) $8.65
Current Price
$1,080.53
Key Data Points
Market Cap
$1.2TMarket cap calculated using publicly traded s outstanding only. Does not include unlisted, private, or dual-class non-traded s. Implied market cap may vary.
Day’s Range
$1044.00 – $1081.04
52wk Range
$154.65 – $1255.00
Volume
22M
Avg Vol
38M
Gross Margin
72.60%
Dividend Yield
0.05%
Demand from AI hyperscalers has consumed all production capacity and then some, with many companies seeing their order backlogs overrun by multiple years. This has created soaring memory chip prices as companies attempt to get their hands on as much memory as possible, and it isn’t going to get better any time soon.
Nvidia (NVDA -0.41%) estimates that next year, the big five AI hyperscalers will spend $1.3 trillion on data center capital expenditures, up from $800 billion the year before. That means that demand for memory chips will rise alongside it, further stretching this industry.
Micron is working to alleviate this shortage by building multiple production facilities, but they won’t come online until mid-2027 or 2028. Even with those new facilities, there’s no guarantee that there will be enough capacity to meet current demand. Sandisk is also investing $31 billion into a new production facility to increase its supply.
The AI arms race is far from over, and it still has several years to go. These two wouldn’t be building new production facilities if there wasn’t more room to grow.
2. The AI arms race is far from over
While more supply is coming online to ease the supply crunch in the industry, the reality is the AI arms race is far from over. Nvidia estimates that there will be $3 trillion to $4 trillion in data center capital expenditures by 2030, significantly higher than today’s level. Even if the memory chip suppliers build out enough production capacity to meet current demand, it could be eclipsed in a few years.
Expand

NASDAQ: SNDK
Sandisk
Premium Feature
Moneyball Superscore
78/100
Today’s Change
(-3.46%) $-62.95
Current Price
$1,753.62
Key Data Points
Market Cap
$266BMarket cap calculated using publicly traded s outstanding only. Does not include unlisted, private, or dual-class non-traded s. Implied market cap may vary.
Day’s Range
$1726.39 – $1802.99
52wk Range
$93.53 – $2354.39
Volume
8.2M
Avg Vol
13.8M
Gross Margin
71.47%
If they have sufficient production to meet demand, their production facilities will still operate near maximum capacity, allowing them to maintain elevated margins and making their stocks solid investments.
3. The latest demand curve may have reset the industry
Lastly, AI has changed the outlook of many in the computing supply industry. It’s possible that there is a brand new massive base load for chip producers. This will increase the vast amount of products each company manufactures each year, which means some of these gains are here to stay.
The question is how much of the new business that has come online is sustainable over the long term. The market has doubts about that, which is why each company trades at a pretty low forward earnings multiple.
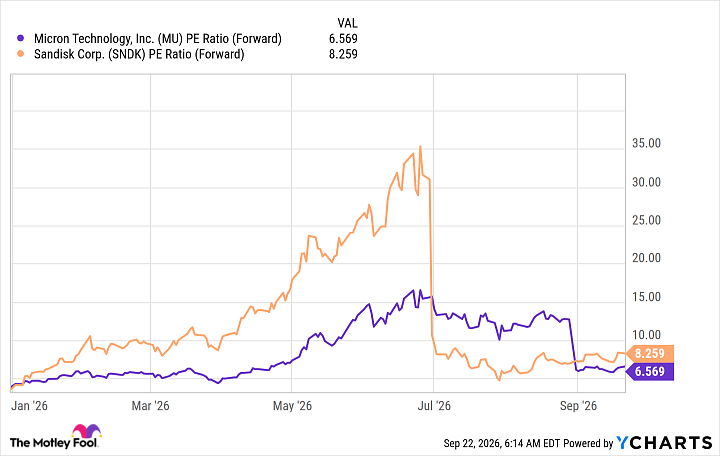
MU PE Ratio (Forward) data by YCharts
If today’s rates become the new industry base, there is plenty of room for these stocks to soar. Even if they’re half of today’s demand, these stocks would still be cheap, making them viable candidates for long-term investing.
Read Next
•By Marc Guberti
Will Sandisk or Micron Perform a Stock Split Next Year?

•By Patrick Sanders
Micron Stock Gets a Big Wall Street Boost Ahead of Earnings
•By Harsh Chauhan
Prediction: Micron Stock Will Double Within 2 Years

•By Daniel Sparks
3 Stocks That Get Paid More When Memory Prices Rise. I’d Buy Only 1 of Them.
•By Micah Zimmerman
3 Warning Signs That Micron Investors Shouldn’t Ignore
•By Harsh Chauhan
Micron vs. Sandisk: Which AI Memory Stock Has More Room to Run?
About the Author

Keithen Drury is a contributing Motley Fool technology analyst covering AI, semiconductors, cybersecurity, and SaaS stocks. In addition to The Motley Fool, Keithen is a mechanical engineer and has held roles at Honeywell and smaller industrial companies Brand Hydraulics and Lincoln Industries. He holds a bachelor’s degree in mechanical engineering from Dordt University.
Stocks Mentioned

Micron Technology
NASDAQ: MU
$1,080.53
(+0.81%)+$8.65

Motley Fool Stock Advisor’s Latest Pick
—% Avg Return

Nvidia
NASDAQ: NVDA
$224.58
(-0.41%)-$0.93

Sandisk
NASDAQ: SNDK
$1,753.62
(-3.46%)-$62.95
*Average returns of all recommendations since inception. Cost basis and return based on previous market day close.
Sumber Artikel:
Fool.com

