

▲ S&P 500 +—%|▲ Stock Advisor +—%Join The Motley Fool
The interesting thing about RTX’s Raytheon, and why I think RTX is a better buy than Lockheed Martin, comes down to having relatively less exposure to some of the fixed-price development programs that have led to massive cost overruns and charges at Lockheed and Boeing (BA -0.79%) in recent years. For example, Raytheon has proven technologies such as Tomahawk missiles and advanced medium-range air-to-air missiles (AMRAAMs) in its backlog, which, although subject to supply chain risk, pose significantly fewer challenges than the F-35 (Lockheed) or next-generation strike fighters (Boeing) pose.
Moreover, Pratt’s commercial engines, primarily the geared turbofan (GTF) on the Airbus A320neo, can generate decades of lucrative aftermarket revenue, and Collins is a major player in commercial aerospace across many platforms.
Expand

NYSE: RTX
RTX
Premium Feature
Moneyball Superscore
78/100
Today’s Change
(-1.65%) $-3.03
Current Price
$180.26
Key Data Points
Market Cap
$243BMarket cap calculated using publicly traded s outstanding only. Does not include unlisted, private, or dual-class non-traded s. Implied market cap may vary.
Day’s Range
$179.95 – $183.54
52wk Range
$155.64 – $226.88
Volume
4.2M
Avg Vol
4.4M
Gross Margin
20.35%
Dividend Yield
1.56%
GE Aerospace for its dominant position in aircraft engines
GE Aerospace’s management expects to generate $1.6 billion to $1.7 billion in operating profit from its defense and propulsion technologies business in 2026, compared to $10.25 billion to $10.35 billion from its commercial engines and services segment. Clearly, defense is not the primary reason to buy GE Aerospace stock. Still, it is a profitable business that is also highly complementary to the commercial aerospace business, with commercial and defense engines sharing core technologies, materials, and supply chains, and with stronger bargaining power when negotiating with suppliers.
Meanwhile, the commercial aircraft engine business, RTX, has a long tail of lucrative recurring aftermarket revenue (engines can be used for more than 40 years) driven by its dominant position in the industry.
Image source: Getty Images.
Boeing for the turnaround
The case for buying Boeing isn’t based on flawless execution in its commercial airplane business (the high-profile groundings and delays, notably on the 777C) or even in its defense business (barely profitable after years of challenges with fixed-price development contracts). Instead, it rests on the idea that CEO Kelly Ortberg is improving execution and leveraging Boeing’s $715 billion backlog, including $597 billion in commercial airplanes.
There are clear signs of progress with delivery rates ramping up on the 737 MAX, and management expects a 2.5% profit margin in the defense business in 2026 as it works through the problematic defense programs. Moreover, based on analyst estimates, Boeing trades at a clear discount to the sector, implying meaningful upside potential if Ortberg continues to turn the business around.
Expand

NYSE: BA
Boeing
Premium Feature
Moneyball Superscore
47/100
Today’s Change
(-0.79%) $-1.50
Current Price
$188.32
Key Data Points
Market Cap
$149BMarket cap calculated using publicly traded s outstanding only. Does not include unlisted, private, or dual-class non-traded s. Implied market cap may vary.
Day’s Range
$186.20 – $188.84
52wk Range
$176.77 – $254.35
Volume
6.4M
Avg Vol
6.5M
Gross Margin
4.71%
Hexcel for composite content growth
Boeing, Airbus, and their suppliers make up the bulk of demand for Hexcel‘s (HXL -2.45%) advanced composites, and “defense, space, and other” accounts for 37% of its overall revenue. Hexcel is essentially a play on improving aircraft build rates and increasing the content of advanced composites on newer aircraft. This clear trend continues to grow with each new generation of aircraft.
While the company has suffered in previous years as aircraft build rates have slowed, notably for widebodies that use more composites, backlogs at Boeing and Airbus will drive future demand.
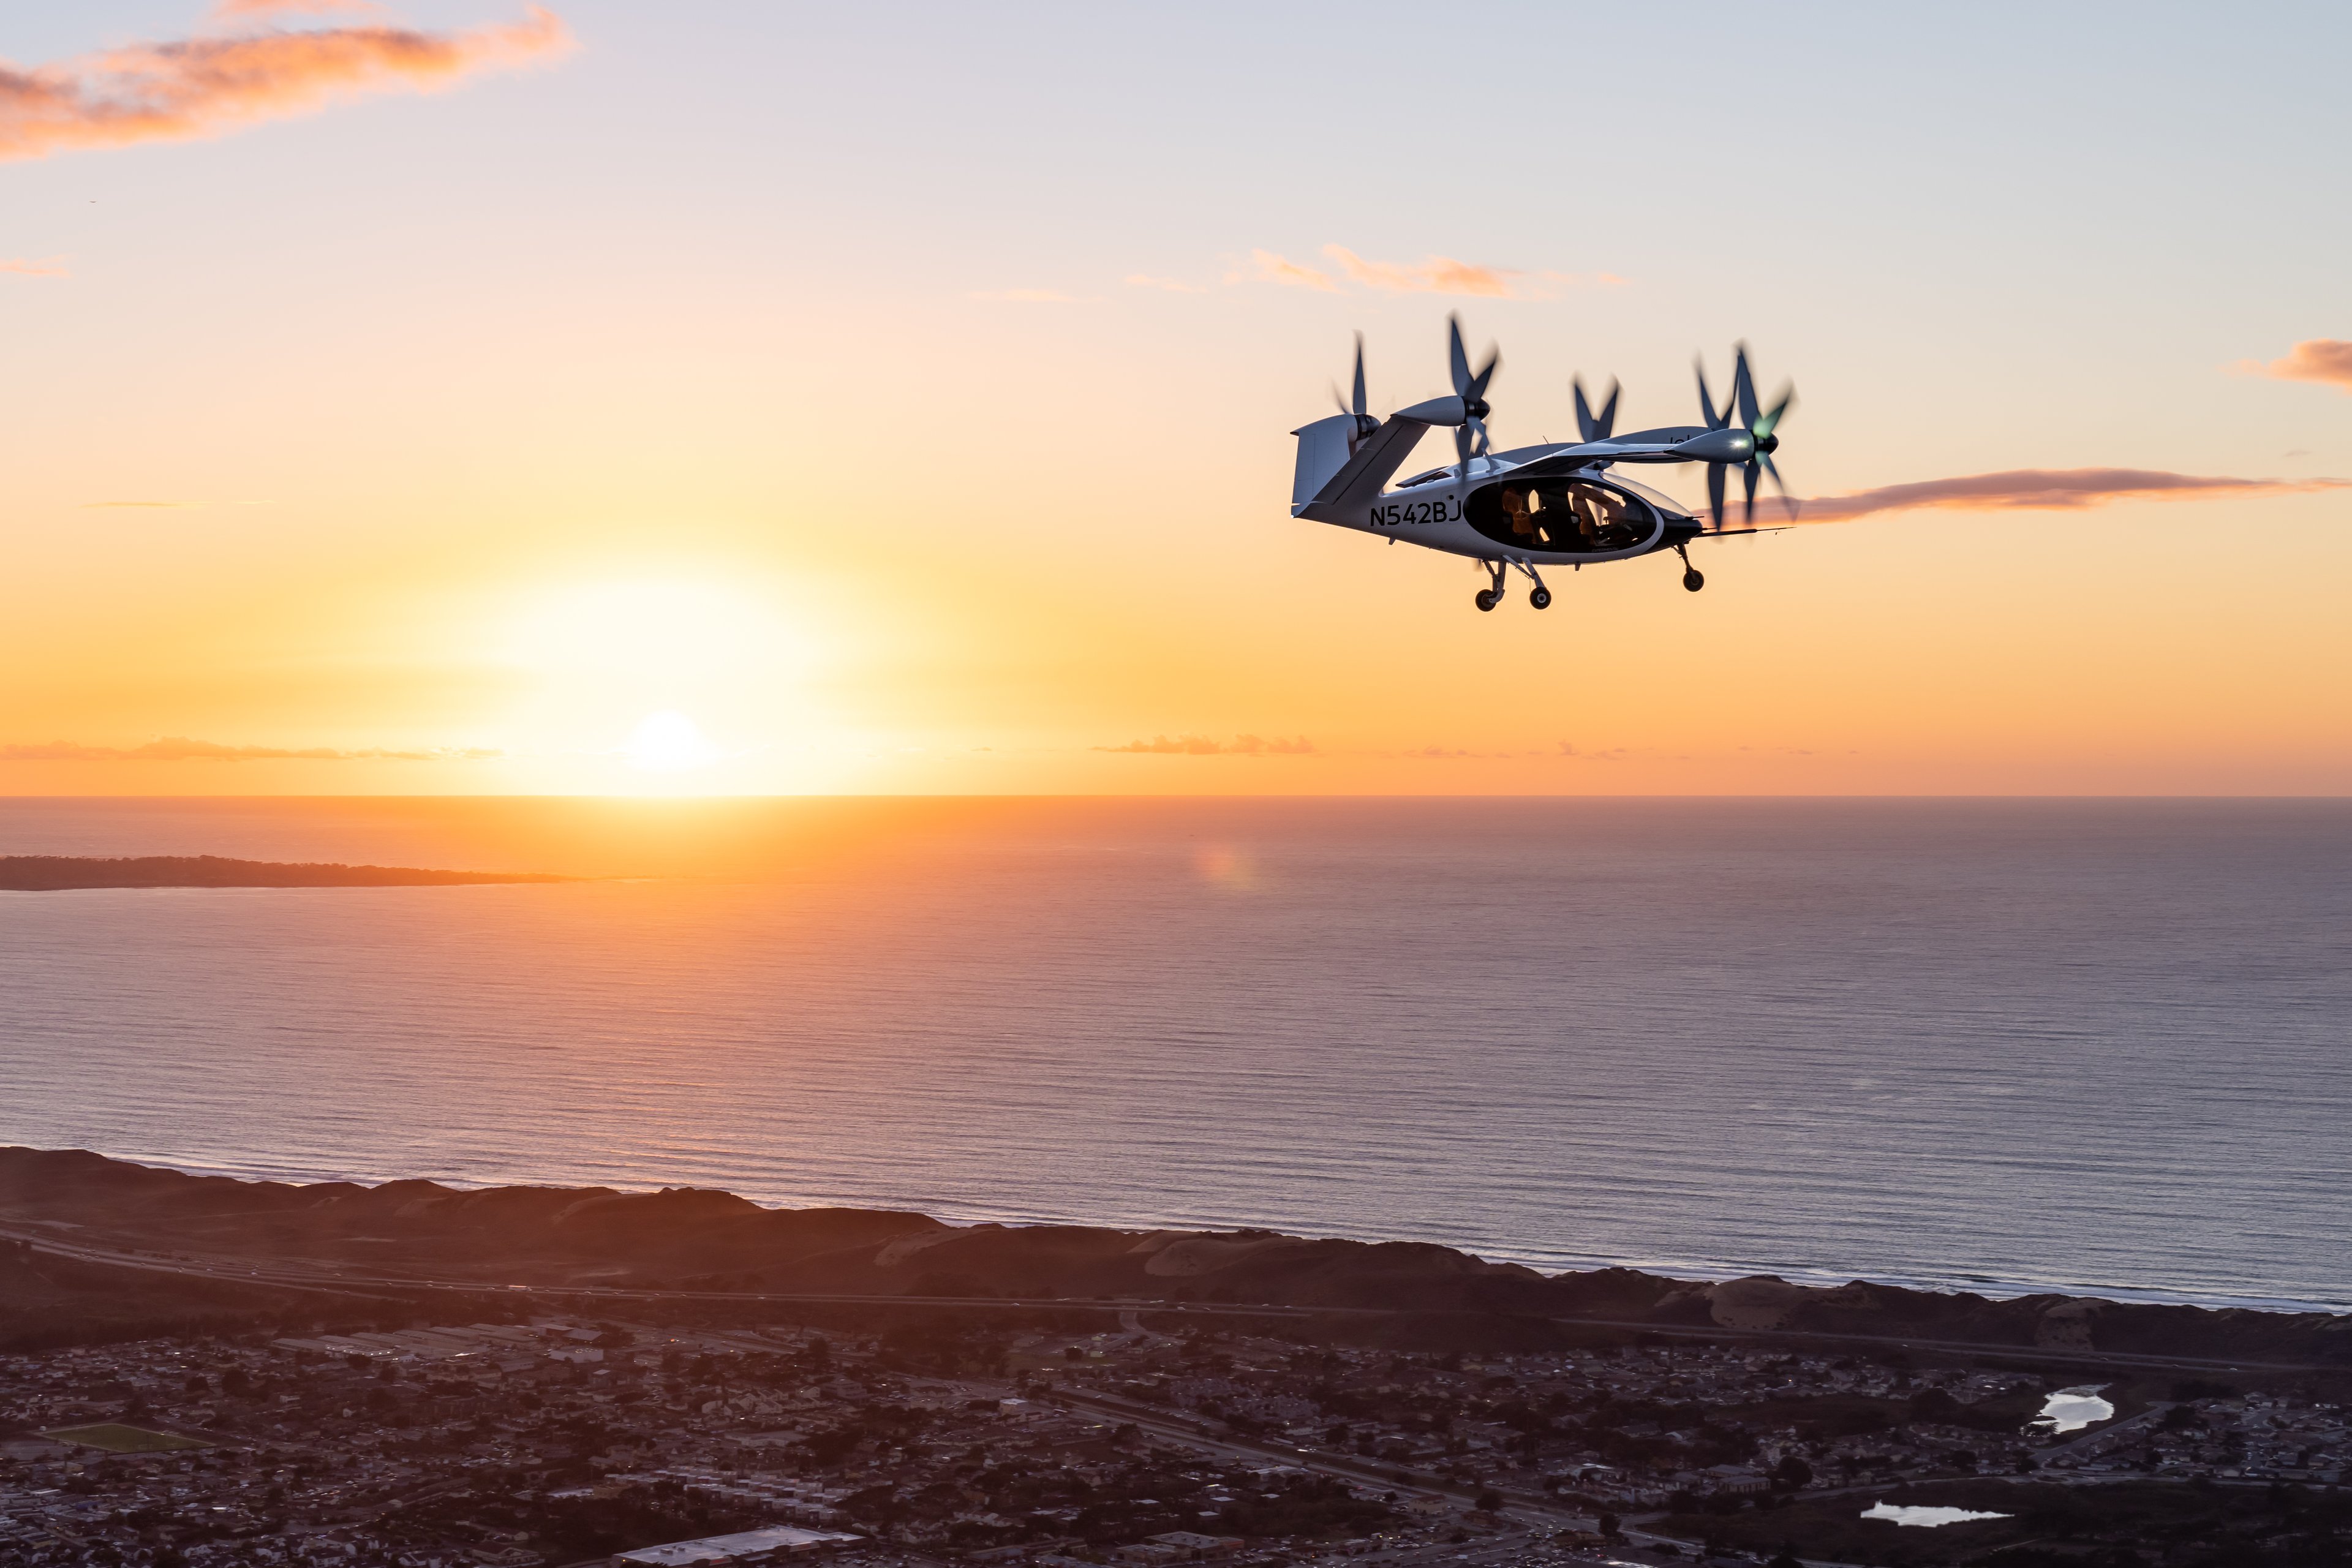
Image source: Joby Aviation.
Joby Aviation for eVTOL growth
The case for buying Joby Aviation (JOBY -0.52%) isn’t based on its long-term defense business. Instead, the company needs to get its commercial electric vertical take-off and landing (eVTOL) aircraft certified and in operation as it slowly builds out its transportation-as-a-service model. It’s an exciting business, but it will take time and cash before it turns a profit. That’s why eVTOL companies Joby and Archer Aviation are increasingly turning to defense work, which offers more immediate upfront revenue.
In fact, Joby recently acquired Resonant Sciences, a radio-frequency (RF) sensing and signal-processing defense technology company, for $500 million. Resonant will become Joby’s defense business, with the intent to “unite Joby’s dual-use aircraft, propulsion and autonomy technologies with Resonant’s radio frequency (RF), sensing and mission systems capabilities.”
AAR Corp., buy the dip
If Hexcel and Boeing are original equipment (OE) plays, and GE Aerospace and RTX are a mix of both, then aviation services company AAR Corp. (AIR -4.24%) is on the aftermarket end of the spectrum. It generates about 27% of its sales from government sources, mainly military. The company made the news recently after its stock fell ing the planned acquisition of a majority stake in the complementary maintenance, repair, and overhaul business MRO Holdings.
However, the deal makes perfect sense, comes with a reasonable price tag, and promises to expand AAR’s geographic reach, notably in Latin America, and its offerings, making it the world’s largest maintenance, repair, and overhaul company. I think the dip is a buying opportunity in a company expanding its footprint in an expanding market.
Read Next
•By Lyle Daly
The Largest Industrials Companies by Market Cap in October 2026

•By Brendan Coffey
GE Aerospace vs. SpaceX: Which Aerospace Giant Is a Better Stock Buy in 2026?

•By Brendan Coffey
GE Aerospace vs. Lockheed Martin: Which Industrials Stock Is a Better Buy in 2026?

•By Brendan Coffey
Boeing vs. GE Aerospace: Which Aerospace Stock Is a Better Buy in 2026?

•By Brendan Coffey
AST SpaceMobile vs. GE Aerospace: Which Industrials Stock Is a Better Buy in 2026?
•By Brendan Coffey
Firefly Aerospace vs. GE Aerospace: Which Industrials Stock Is a Better Buy in 2026?
About the Author

Lee Samaha is a contributing Stock Market Analyst at The Motley Fool covering industrials, electricals, energy, materials, transportation, and infrastructure stocks. Prior to The Motley Fool, Lee was a Civil Engineer and Investment Manager. He holds a Bachelor of Civil and Structural Engineering from Southampton University and a Certificate in Investment Management from Chartered Institute for Securities & Investment. Lee first cut his investing teeth on The Motley Fool bulletin boards (commonly referred to as the “Fool Boards,”) and he’s infinitely grateful to all of the investors he learned from in this powerful investing community.
Stocks Mentioned

GE Aerospace
NYSE: GE
$303.62
(-1.86%)-$5.77

Motley Fool Stock Advisor’s Latest Pick
—% Avg Return

Boeing
NYSE: BA
$188.32
(-0.79%)-$1.50

RTX
NYSE: RTX
$180.26
(-1.65%)-$3.03

Lockheed Martin
NYSE: LMT
$499.22
(-2.14%)-$10.90

Hexcel
NYSE: HXL
$83.90
(-2.45%)-$2.11

Airbus SE
OTC: EADSY
$52.38
(-0.46%)-$0.24

Aar
NYSE: AIR
$99.62
(-4.24%)-$4.41

Joby Aviation
NYSE: JOBY
$5.75
(-0.52%)-$0.03

Archer Aviation
NYSE: ACHR
$4.67
(+0.43%)+$0.02
*Average returns of all recommendations since inception. Cost basis and return based on previous market day close.
Premium Investing Services
Invest better with The Motley Fool. Get stock recommendations, portfolio guidance, and more from The Motley Fool’s premium services.
Sumber Artikel:
Fool.com

