 Andrew Aitchison/In Pictures Ltd./Corbis via Getty Images
Listen to this commentary Please log in to listen to this commentary 0:00 / 0:00 Audio unavailable
Some argue that stablecoins are better for cross-border payments. They point out that remittances sent in the form of a dollar-backed stablecoin could reach, say, Kampala from anywhere else in the world in seconds and at low cost. But the recipient would still need to convert the stablecoin into Ugandan shillings, and the market for doing so is a fraction of the size of the market banks and money-transfer operators draw on, with worse exchange rates. As a result, money-transfer operators Wise or Remitly generally offer better value end-to-end; they are certainly easier to access for most low-income recipients.
Cross-border bank transfers are still slower and more expensive than such operators (and stablecoins), but this can be addressed by linking domestic instant-payment systems, as envisioned in the G20 Roadmap for Cross-Border Payments. This approach is already being implemented in some regions: the Nexus payment system, for example, links India, Malaysia, the Philippines, Singapore, and Thailand.
Secure your copy of PS Quarterly: Slopocalypse Now
AI-generated content already accounts for half the articles published online, and not even digital forensics experts can tell what’s real anymore. Can those still offering a humanistic vision of online life make themselves heard over the din?
SUBSCRIBE & $50
Of course, financial inclusion entails more than just payments. Financial systems must offer all consumers a range of products that meet their needs. Fortunately, we may well be on the verge of an explosion in new financial products for low-income customers. The key ingredient is data: critical information about an individual (d with their consent) can increasingly be used to build tailored financial products.
This approach is already beginning to transform lives. In Ethiopia, a regulatory reform on data exchange enabled the Cooperative Bank of Oromia to launch a lending product called Michu, built not on collateral but on transaction data, and tailored to the borrower’s specific needs. Within a year, Michu had built a customer base that was more than one-third women.
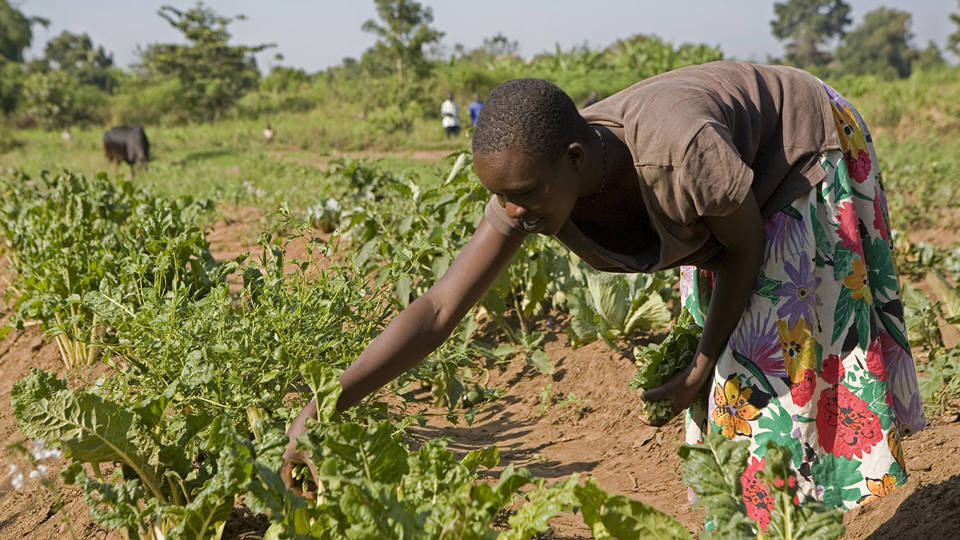
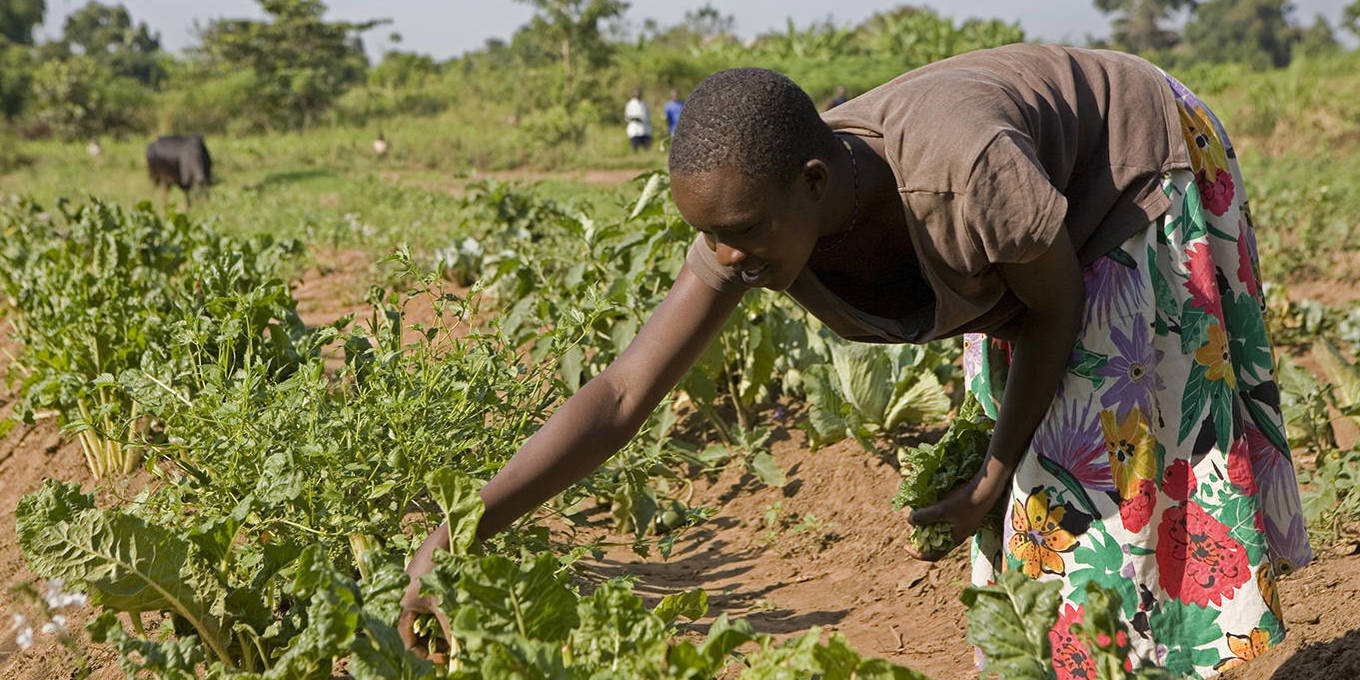
For farmers—who typically do not have extensive transaction histories, since most agriculture payments are still made with cash—different types of data could be used. Governments already increasingly collect data on the land farmers hold, the crops they grow, and even the rainfall on their fields (verified via satellites), primarily to provide advice. d with consent, such data could enable a lender not only to estimate farmers’ current income accurately, but also to structure loan-repayments to match their cash-flow cycle.
Lenders could even use these data and advice models to identify opportunities for individual farmers to increase their incomes, such as by installing solar-irrigation pumps. Linking lending to such opportunities would lower the price of the loan, reduce the risk to the lender, and add extra value for the farmer. The same data could be used to price insurance that pays out the moment satellite imagery confirms a drought, instead of waiting for a claims adjuster. It is early days, but initiatives along these lines in Ethiopia and Kenya offer reason to hope that this approach can deliver the financial products farmers need. Ethiopia’s National Agri-Finance Implementation Roadmap (NAFIR), launched jointly by the National Bank of Ethiopia and the Ministry of Agriculture, will provide lenders with a wide range of data from the OpenAgriNet system, structured in a way to be useful to lenders.
Ultimately, what increasing financial inclusion requires does not involve stablecoins. Policymakers must develop interoperable payment infrastructure to enable banks, mobile-money providers, and fintech firms to exchange money freely, domestically and across borders. Funders should support the strengthening of regulatory capacity and data infrastructure—less glamorous than launching a stablecoin pilot, but far more impactful. And financial institutions should leverage new data to design financial products for low-income people’s needs and opportunities, rather than what they own or their past transactions.
Future progress on financial inclusion will not be decided by which digital currency wins. It will be decided by whether the financial system is sufficiently open, competitive, and interconnected.
Help us strengthen our reporting on global health and development by taking a short survey.
Take Survey
Featured
-
Distorted Intelligence at the AI Frontier
Sep 28, 2026 Daron Acemoglu
-
Is Another Eurozone Debt Crisis Looming?
Sep 30, 2026 Desmond Lachman
-
What Killed Liberalism?
Sep 25, 2026 Gene Frieda
-
An EU–Canada Partnership Against Coercion
Sep 28, 2026 Alberto Alemanno
-
The Great AI Gamble
Sep 25, 2026 Harold James
https://prosyn.org/oZ61K4G
It appears that you have not yet updated your first and last name. If you would to update your name, please do so here.
Please wait, fetching the form
Please wait, fetching the form
Please wait, fetching the form
Please wait, fetching the form
Please wait, fetching the form
Please wait, fetching the form
Please wait, fetching the form
Sumber Artikel:
Project-syndicate.org