 US Navy via Getty Images
Listen to this commentary Please log in to listen to this commentary 0:00 / 0:00 Audio unavailable
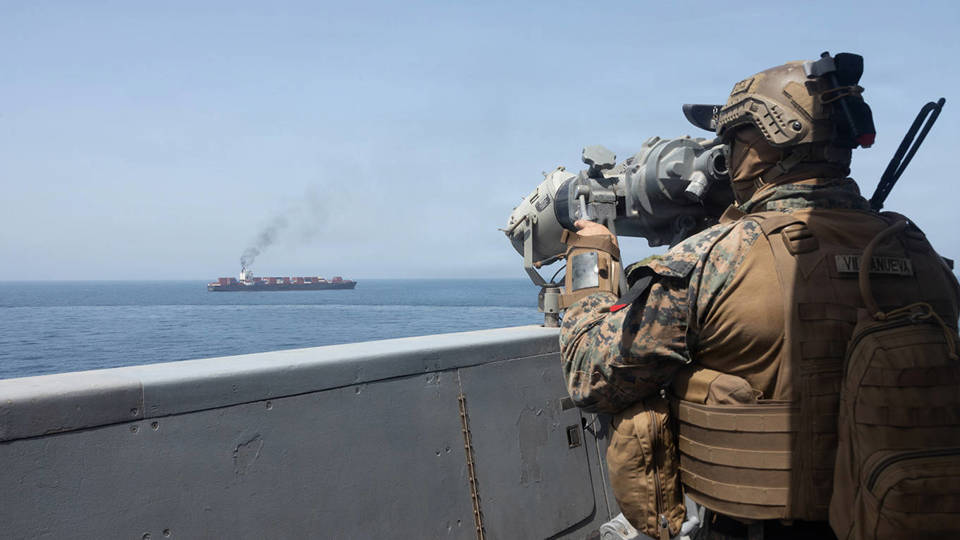
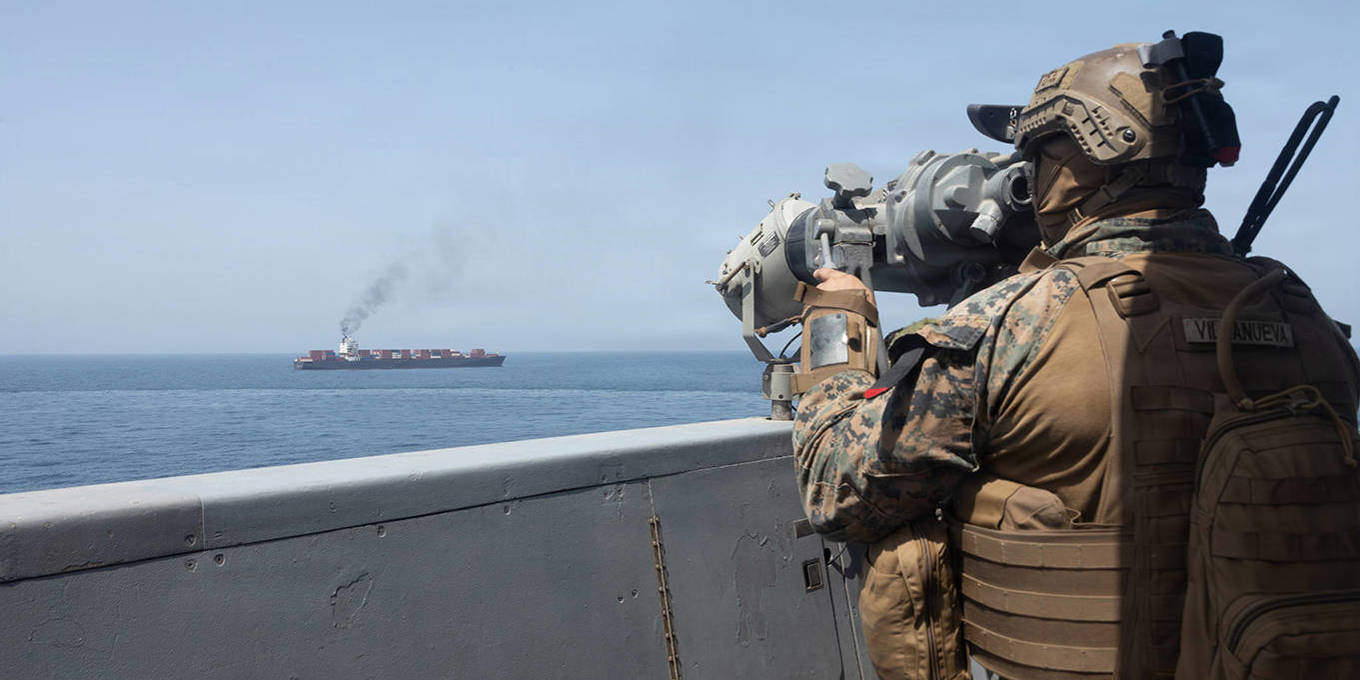
But trade can also create dependencies that become vulnerabilities. Countries might rely on a few geographically distant suppliers or routes that are exposed to disruption. The Strait of Hormuz is far from the world’s only maritime chokepoint; two-thirds of energy trade crosses at least one.
Our analysis of 65 countries suggests that, in the event of disruption, response capacity is critical, with short-term buffers (stockpiles) and longer-term solutions (such as domestic resources, alternative suppliers, or the ability to substitute fuels) all playing a role. The range of factors at play helps to explain why headline import dependence can be misleading: two countries that import the same amount of energy may have very different response capacities, because one has larger stockpiles or better access to alternatives.
Secure your copy of PS Quarterly: Slopocalypse Now
AI-generated content already accounts for half the articles published online, and not even digital forensics experts can tell what’s real anymore. Can those still offering a humanistic vision of online life make themselves heard over the din?
SUBSCRIBE & $50
Even a large net exporter might be vulnerable to disruptions if it relies on imports of specific fuels. Brazil exports crude oil, but imports about a quarter of its diesel. Indonesia exports LNG, but depends on imported oil, and has limited storage capacity for refined fuels.
Governments are already moving to reduce exposures and strengthen their response capacity. For example, Pakistan is considering the creation of a strategic petroleum reserve. India and South Africa are increasing theirs. And Indonesia aims to increase its fuel-storage capacity from roughly 25 days of consumption to 90.
But inventories alone cannot deliver long-term energy security. wise, while other measures can reduce exposure or strengthen response capacity, they each have limits.
Electrification and domestically-produced clean energy can structurally reduce fuel-import dependence. We estimate that currently viable low-emissions technologies could, in theory, displace imports equivalent to 26–31% of today’s global oil and gas consumption. In practice, technology, economics, upfront investment, and asset turnover will affect the speed and scale of progress on substitution.
New oil and gas production may also reduce import dependence, but not everyone has the right resources or economic conditions. Domestic coal can backstop some power systems, but with important consequences for emissions and air quality. Reconfiguring trade can diversify suppliers and routes, but it requires infrastructure that can itself be disrupted.
Put simply, there is no single prescription for energy security. Some strategies will seek to reduce dependencies through substitution; others will build buffers, domestic supply, or alternative suppliers and routes. Many will do both.
It is up to policymakers to identify which vulnerabilities could lead to the greatest economic and social damage, and where limited investment can buy the most resilience. This is particularly true for developing economies, which often lack fiscal space and access to affordable capital.
While investments will be costly, the impact of energy shocks could prove even costlier without them. In South Africa, load shedding reduced GDP growth by an estimated 1–3 percentage points in 2022. How much the current energy shock will end up costing vulnerable emerging economies remains to be seen, but the total bill will surely be substantial.
Cooperation can help limited resources go further. Regional coalitions can help countries pool reserves, coordinate emergency responses, build interconnected infrastructure, or secure alternative supplies at better rates. ASEAN countries are already exploring the possibility of creating a regional fuel reserve in response to the Hormuz crisis.
Companies face the same challenge, but on a different scale. Their vulnerability may hinge on one fuel, feedstock, supplier, port, or production site. They can stress-test those exposures and determine where flexible inputs, alternative suppliers, inventories, diversified production, or efficiency justify investment—including for the continuity and revenues they can preserve during disruption.
The current energy shock will not be the last. Only by investing in resilience today—making deliberate choices about which dependencies to address and how—can countries and companies ensure that, when the next shock hits, they have options.
Featured
-
Trump’s Iran Sanctions Have a China Problem
Sep 18, 2026 Zongyuan Zoe Liu
-
Preventing an AI World War
Sep 22, 2026 S. Alex Yang & Angela Huyue Zhang
-
Is Germany’s Firewall Collapsing?
Sep 22, 2026 Jan-Werner Mueller
-
Are Mexicans Really Better Off Under Claudia Sheinbaum?
Sep 17, 2026 Guillermo Ortiz
-
What Xi Really Wants From Trump
Sep 22, 2026 Steve Tsang
https://prosyn.org/VX7VwFS
It appears that you have not yet updated your first and last name. If you would to update your name, please do so here.
Please wait, fetching the form
Please wait, fetching the form
Please wait, fetching the form
Please wait, fetching the form
Please wait, fetching the form
Please wait, fetching the form
Please wait, fetching the form
Sumber Artikel:
Project-syndicate.org