

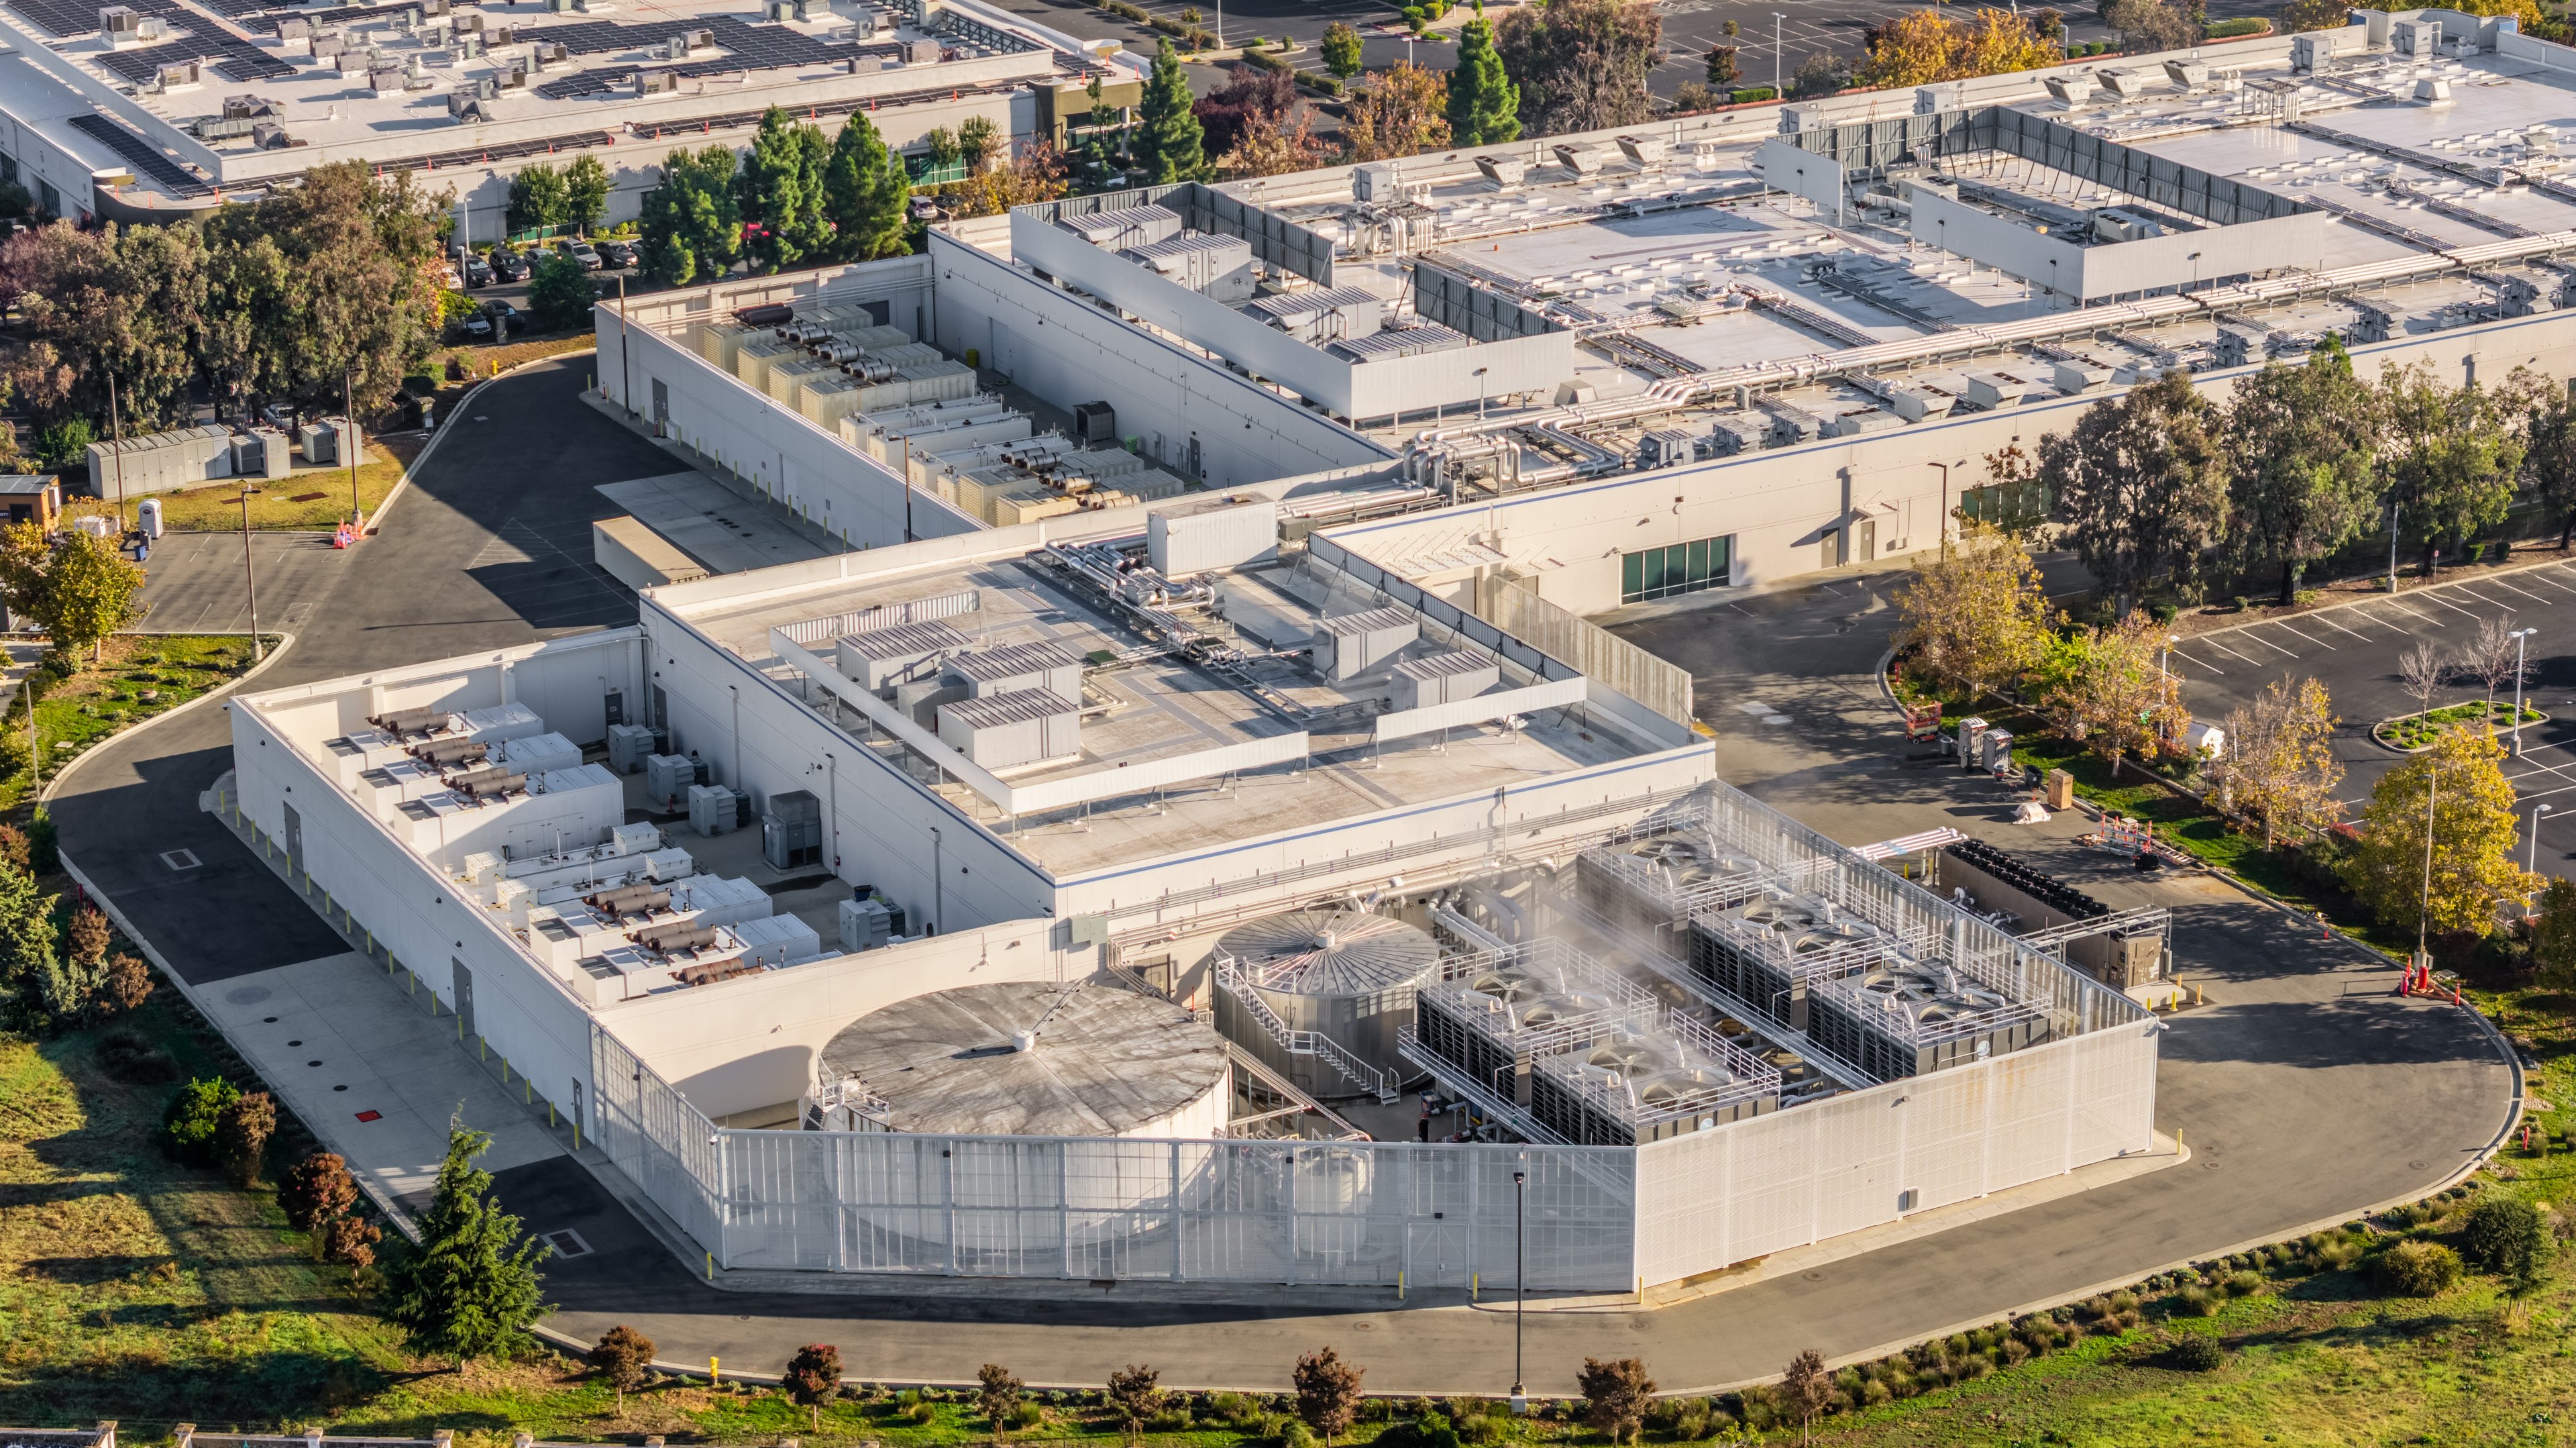
Image source: Getty Images.
The index pop has mostly disappeared
The case for acting quickly is mechanical. After all, about $13 trillion in assets were indexed to the S&P 500 at the end of 2024, according to S&P’s own tally.
Funds that replicate the index don’t get to weigh the price. They have to own Bloom, and they typically make the swap in the closing auction on the final trading day before a change takes effect — this Friday, Sept. 18, in Bloom’s case.
But that buying is well telegraphed, and investors have learned to get ahead of it. Researchers at Harvard Business School found that the additional return from a stock joining the S&P 500 declined from an average of 7.4% in the 1990s to 0.3% in the decade through 2020. Put another way, the market now absorbs the index funds’ buying without much of a pop.
Bloom’s own trading matches that pattern. s jumped almost 10% in the first trading session after the announcement. As of this writing, they have given back most of it and trade about 4% above where they closed before the news.
Index membership changes who holds Bloom’s s. What matters more, I think, is that it doesn’t change what the business earns.
Accelerating growth
On that score, Bloom has been delivering. The company passed $1 billion of quarterly revenue for the first time in the second quarter, with sales up 166% year over year — and faster than the first quarter’s 130%. Not only did growth speed up, but Bloom also turned a profit. Operating income came in at $182.2 million, compared with a small loss a year before. Earnings per swung to $0.62 from an $0.18 loss.
The full-year outlook has risen just as fast. Management’s guidance pointed to about 60% revenue growth when the year began. In April, the company raised the midpoint to about 80%.
And in July it raised guidance once more, to $3.9 billion to $4.2 billion — about 100% growth at the midpoint compared with the $2.02 billion of revenue Bloom reported in 2025. The company also now expects $800 million to $900 million of non-GAAP (adjusted) operating income this year, nearly double what it projected in February.
The buyers behind this surge are AI data centers and the companies building them. In the second-quarter release, CEO KR Sridhar said Bloom’s power systems have been validated by “all the major US hyperscalers” (the largest cloud computing companies) and called the company “a standard for AI onsite power.”
Expand

NYSE: BE
Bloom Energy
Premium Feature
Moneyball Superscore
81/100
Today’s Change
(0.90%) $2.30
Current Price
$259.35
Key Data Points
Market Cap
$76BMarket cap calculated using publicly traded s outstanding only. Does not include unlisted, private, or dual-class non-traded s. Implied market cap may vary.
Day’s Range
$257.09 – $269.83
52wk Range
$61.37 – $351.28
Volume
10.7M
Avg Vol
15.2M
Gross Margin
31.22%
Too pricey?
The market, though, has noticed all of this. At about $263, Bloom stock’s forward price-to-earnings ratio (its price measured against next year’s expected earnings) is about 53.
At that price, investors have arguably already paid for this year’s doubling and are counting on years of robust growth afterward. If spending on AI data centers cools, Bloom’s growth and its stock price could both fall fast. Concerns about exactly that were behind Monday’s slide.
Of course, the slowdown may never come. Management sees demand accelerating, and the guidance raises back that up. But at this price, Bloom has to keep executing at a pace few companies can maintain for long.
So, should you buy Bloom Energy stock before it joins the S&P 500? If the index change is the reason, I don’t think so. The buying from index funds is a one-time event, and history says it no longer provides much of a boost.
In the end, if you believe in the business, s will still be there after the funds have finished buying. As for me, the price is too rich. I’d rather wait for a better entry point than buy just ahead of the index funds. If the stock pulls back meaningfully, or if earnings start catching up with the price, I’d take another look.
Read Next
•By Rick Orford
Bloom Energy Isn’t Selling Power. It’s Selling Time.

•By Sara Appino
Bloom Energy vs. NANO Nuclear Energy: Which Stock Is a Better Buy in 2026?

•By Sara Appino
Bloom Energy vs. GE Vernova: Which Stock Is a Better Buy in 2026?

•By Sara Appino
Bloom Energy vs. Diamondback Energy: Which Industrials Stock Is a Better Buy in 2026?
•By Sara Appino
Bloom Energy vs. Oklo: Which Industrials Stock Is a Better Buy in 2026?
•By Lawrence Nga
The AI Company You Haven’t Heard of — But Should Keep on Your Radar
About the Author

Daniel Sparks is a contributing Motley Fool stock market analyst covering technology, industrials, financials, and consumer goods. Daniel is the owner and chief investment officer of Sparks Capital Management. He holds a master’s degree in business administration from Colorado State University. The Globe and Mail profiled him and his investing philosophy in an article titled, “This stock picker is outperforming nearly everybody else. Here’s how he is doing it.”
Stocks Mentioned

Bloom Energy
NYSE: BE
$259.35
(+0.90%)+$2.30

Motley Fool Stock Advisor’s Latest Pick
—% Avg Return
*Average returns of all recommendations since inception. Cost basis and return based on previous market day close.
Sumber Artikel:
Fool.com

